Starting from · ₹799 GST Amendment Quick Amendment plan
STARTING FROM₹799
FEE TOLD UPFRONTFree first call
!Late GST return?Late fee and interest run till you file
Since 2018Trusted Experience
980+Experts Connected
220+Cities Served
1164+Agents Available
12000+Founders Trusted
S
Srishti Magoo
★★★★★
Excellent experience with TaxCaller for filing my &
my family members ITR returns. The entire process was
smooth, quick and hassle-free. They are professional,
knowledgeable and guided me through every step with patience.
O
obeid sait
★★★★★
The team has handled my taxes for the past three years,
and it's been a wonderful, hassle-free experience.
Thank you for your consistently quick and efficient service.
P
Pushkar
★★★★★
They are among the best in their field. Their work culture
is highly professional, and their client service is smooth
and reliable. They can confidently be relied on to get the job done.
P
Prasad Sheth
★★★★★
Excellent experience with TaxCaller! The ITR filing
process was smooth, quick, and completely hassle-free.
The CA was knowledgeable, responsive, and explained everything clearly.
A
Apoorv Bansal
★★★★★
Excellent service for ITR filing. The team was highly
professional, responsive, and guided me through the entire
process smoothly. My return was filed accurately and on time.
A
Abhishek Kumar
★★★★★
I was searching for a good CA firm in Ghaziabad and found
TaxCaller. The experience was excellent from start to finish.
The team is responsive, transparent, and genuinely helpful.
U
uma pandey
★★★★★
Great service! TaxCaller India made the entire ITR filing
process quick, smooth, and hassle-free. They answered all
my queries patiently and ensured maximum accuracy.
T
tanu mittal
★★★★★
Excellent job! We've been connected for many years,
and your success truly makes me happy. You are an
incredibly intelligent person. Keep shining, keep growing.
B
Bhanu Pratap Maurya
★★★★★
I am filing my ITR since past 3 years with Abhinav and
Firm is known as TaxCaller and they are professional
interms of ITR rules. They will explain and tell you all
the information.
A
ashish Sharma
★★★★★
I am providing my honest reviews:
No.1 service ...
A
AARYAN GROUP
★★★★★
Honestly, finding a good CA firm in Ghaziabad was
confusing, but TaxCaller India made it simple.
I contacted them for GST work and the experience was smooth.
N
News Speaks
★★★★★
If you're looking for a reliable CA firm in Ghaziabad,
TaxCaller India is a great choice. They provide complete
taxation and compliance solutions including GST.
A
Anshul Chaprana
★★★★★
Got my GST registration done through TaxCaller CA firm.
Process was quite smooth, they guided properly on documents
and didn't waste time. Overall good experience.
How we work
Online · Call · WhatsApp
Quick answer
GST amendment is changing the details of your GST registration by filing Form GST REG-14 on the GST portal within 15 days of the change. Since 1 November 2026, most changes take effect on submission after OTP and online checks. Only a change of principal place of business still needs officer approval. No government fee applies.
Reviewed by Abhinay Rai · Updated 15 Nov 2026
Pick a plan that fits
Quick Amendment
One change that takes effect on submission, such as bank, signatory, trade name or contact details
Advice on fresh registration where the PAN changes
Post-amendment checklist for e-invoice, e-way bill and other licences
Government fees and taxes are extra where applicable. Our expert confirms the final amount on the first call. No hidden charges.
About GST Amendment
A GST amendment lets you change the details in your GST registration without giving up your GSTIN. If you shift your office, add a godown, take in a partner, change the signatory or open a new bank account, the law expects you to update the record. You do it in Form GST REG-14 on the GST portal (gst.gov.in), within 15 days of the change.
The rules changed on 1 November 2026. A new Rule 19 now lets most changes take effect on submission, after OTP and online checks. Only a change of principal place of business still waits for a tax officer. Old guides that talk of core fields needing approval are now partly out of date.
This page explains the new rules in plain words. It covers what you can and cannot change, documents for each change, timelines, OTP rules, common rejection reasons, a worked example and the 2026 updates. TaxCaller's tax experts can file the amendment for you online. For other GST work, see our GST services page.
Complete guide
Choose a topic to open it. Every answer gives the rule or section it comes from.
01 Topic 1 of 20
Rule 19 and Form REG-14: The Legal Basis
GST amendment means changing the details in your existing GST registration through Form GST REG-14 on the GST portal. Your GSTIN stays the same. Only the details behind it change, such as your address, partners, signatory or bank account.
The duty comes from two places in the law:
Section 28 of the CGST Act, 2017: every registered person must tell the proper officer about any change in the information given at registration, in the prescribed form and time.
Rule 19 of the CGST Rules, 2017: it sets the form (REG-14), the 15-day time limit, which changes need an officer, and how the certificate gets amended.
Section 28(3) adds that an amendment under the CGST Act counts as an amendment under the State or Union Territory GST Act too. So you file once, on one portal.
What changes after an amendment
The portal updates your registration record. Where the change appears on the certificate, such as a new address or a new legal name, you can download a fresh certificate from the portal. Your returns, e-way bills and e-invoices then carry the new details.
What it is not
A GST amendment is not a return correction. Mistakes in GSTR-1 or GSTR-3B follow a different route, explained in a short section below. It is also not a new registration. If your PAN changes, the law asks for a fresh GSTIN, not an amendment.
When You Must File: The 15-Day Rule and Common Triggers
You must file Form GST REG-14 within 15 days of the date on which the change happens, under Rule 19(1) of the CGST Rules. The clock starts from the event, not from the day you notice it.
Rule 19(1) covers changes in the particulars given in your original application. That includes Form GST REG-01 for normal taxpayers, CMP-02 for composition, REG-07 for TDS and TCS registrants, REG-09 and REG-10 for non-resident and online service registrants, REG-13 for UIN holders and PCT-01 for GST practitioners.
Common events that need an amendment
Event in your business
What you amend
Office or shop shifts within the same state
Principal place of business
New branch, godown or warehouse in the same state
Additional place of business (add)
Branch closed or godown given up
Additional place of business (delete)
Partner joins or retires, director appointed or resigns
Promoters, partners or directors
Company changes its name with the same PAN
Legal name
New brand name on the board
Trade name
New person to sign GST filings
Authorised signatory
Signatory changes phone number or email
Contact details of the authorised signatory
New current account, or old account closed
Bank account details
New goods or services added
Business activity and HSN or SAC codes
If several things change together, you can usually cover them in one application. The principal place of business is the exception, because it follows the officer route.
Abhinay Rai GST Expert
Have a question on this topic? Ask Abhinay on a free call.
Core and Non-Core Fields: The Old Split and the New Rule 19
Core fields were the registration details that needed a tax officer's approval, and non-core fields were the rest, which updated on filing. From 1 November 2026, the new Rule 19 keeps officer approval only for the principal place of business.
Many guides still use the old labels, so it helps to see both.
Until 31 October 2026
The old Rule 19 named three groups of core fields. Each needed approval from the proper officer within 15 working days:
Legal name of the business, where the PAN did not change
Address of the principal place of business or any additional place of business, within the same state
Addition, deletion or retirement of partners, directors, Karta, managing committee members, trustees or the chief executive
Every other field, such as trade name, bank account, signatory and business activity, was non-core. Those took effect on filing.
From 1 November 2026
Notification 05/2026-Central Tax (G.S.R. 919(E), dated 26 October 2026) substituted Rule 19. The new rule splits changes like this:
Change
Old Rule 19
New Rule 19 (from 1 Nov 2026)
Principal place of business
Officer approval
Officer approval, Rule 19(2)
Principal place of business of a Rule 14A registrant
Officer approval
Effective on submission and online validation, Rule 19(3), from 1 Dec 2026
Additional place of business
Officer approval
Effective on submission and online validation, Rule 19(4)
Legal name (same PAN)
Officer approval
Effective on submission and online validation, Rule 19(4)
Partners, directors, Karta, trustees
Officer approval
Effective on submission and online validation, Rule 19(4)
Trade name, bank, signatory, business activity
On filing
Effective on submission and online validation, Rule 19(4)
Mobile or email of the authorised signatory
After online verification
After online verification under Rule 8(2), Rule 19(6)
In short, the old core and non-core split has become a principal place of business versus everything else split. In practice, online validation covers the OTP checks and the system checks of PAN, DIN and CIN set out in the REG-14 instructions and the GSTN advisory.
You cannot use Form GST REG-14 to change your PAN or the state of your registration. Both are built into the GSTIN itself. A change in either needs a new registration.
Changes that need a fresh GSTIN
PAN change: Rule 19(7) says that where a change in constitution leads to a new PAN, you must apply for fresh registration. Examples are a proprietorship becoming a partnership firm, a firm converting into an LLP, or a firm becoming a company.
State change: GST registration is state-wise under Section 25(1) of the CGST Act. If the business moves to another state, you register in the new state and cancel the old GSTIN if nothing remains there.
Wrong PAN at registration: the PAN cannot be edited. The usual fix is a new registration with the correct PAN and cancellation of the wrong one.
Changes that are blocked for a while
A change of principal place of business is not allowed while the registration is suspended or cancelled, as per the REG-14 instructions.
A Rule 14A registrant cannot keep an amendment pending while withdrawing from that scheme in Form GST REG-32.
Separate registration in the new state. Keep the old GSTIN
Partner joins a firm, firm PAN stays
Amend partners in REG-14
Proprietor forms a partnership or company
New registration under the new PAN. Cancel the old GSTIN
Private company becomes a public company, same PAN
Amend the legal name in REG-14
Business closed for good
Cancellation in REG-16
When the PAN changes because of a sale, merger or transfer of the business with its liabilities, unused input tax credit can be moved to the new GSTIN in Form GST ITC-02 under Section 18(3) and Rule 41. Plan this before you cancel. For a full map of GST services, see our GST services page.
A change of principal place of business within the same state is filed in REG-14 and approved by the proper officer within 15 days of submission, under Rule 19(2). It is the only regular change that still goes to an officer.
How the officer route works
Submission: you file REG-14 with proof of the new premises and complete the OTP checks.
Approval: if all is in order, the officer approves within 15 days of submission and issues an order in Form GST REG-15 (Rule 19(2)(b)).
Query: if something is missing, the officer can issue a notice in Form GST REG-03 within those 15 days (Rule 19(2)(c)).
Reply: you answer in Form GST REG-04 within 7 working days of receiving the notice.
Decision: the officer approves within 7 working days of your reply (Rule 19(2)(d)), or rejects with reasons in Form GST REG-05 (Rule 19(2)(e)).
No reply: if you do not reply in time, the application is treated as rejected and the portal issues Form GST REG-05A (Rule 19(2)(f)).
No action by the officer: if the officer does nothing within the time limit, the certificate is treated as amended (Rule 19(2)(g)).
Under the new rule, the amendment takes effect from the date the officer approves it. So file early. Until approval, your records still show the old address.
What changes on the ground
Display the GSTIN and the registration certificate at the new premises. Update the address on invoices, letterheads and your e-invoice and e-way bill templates. If an officer visits the old address after you move, your business may be marked as not found there. That can lead to suspension and a show cause notice under Section 29(2).
Small taxpayers under Rule 14A
Rule 14A is the simplified registration for applicants whose output tax on supplies to registered persons will not exceed ₹2.5 lakh a month. From 1 December 2026, Rule 19(3) lets such a registrant change the principal place of business on submission and online validation, without an officer. This applies only while the person stays in the Rule 14A scheme.
Shadab GST Expert
Have a question on this topic? Ask Shadab on a free call.
Adding an Additional Place of Business or Warehouse
You add a new branch, godown or warehouse in the same state as an additional place of business in REG-14, and from 1 November 2026 it takes effect on submission and online validation. You no longer wait for an officer.
By default, Section 25(2) of the CGST Act gives a single registration per state, which covers all your places of business in that state. Every one of them must be declared. That includes:
A second shop, branch office or factory in the same state
A godown or warehouse where you keep stock, including a rented one
A third-party or e-commerce operator's warehouse where your goods are stored
A site office for a works contract, if it is a fixed place of business
Why it matters
Goods found at an undeclared place can create trouble during an inspection or an e-way bill check. Your e-way bills also need the right dispatch and delivery addresses. Declaring every place keeps your stock records and movement documents in line with the registration.
New state, new registration
An additional place of business must be in the same state as the GSTIN. A warehouse in another state needs its own registration in that state. Online sellers have a special option since 1 November 2026: Rule 14B lets a seller register in another state using an e-commerce operator's warehouse, subject to its limits and the operator's consent. That is a registration question, so read our GST registration page for it.
Deleting a place
When you close a branch or give up a godown, delete it the same way. A stale address on the record can lead to a failed verification visit.
You can change the legal name in REG-14 only when the PAN stays the same, and the new name must first be updated in the PAN records. The trade name can be changed through the same form at any time.
Legal name
The legal name in GST is the name on your PAN. So the order matters:
Change the name under the law that governs your entity, such as a fresh certificate of incorporation for a company or LLP, or an amended deed for a firm.
Get the PAN record updated with the Income Tax Department.
File REG-14. The portal checks the PAN, and for companies the CIN, online.
If you file before the PAN record changes, the online validation will fail. Under Rule 19(5), a change in legal name applies to every registration under that PAN, in all states.
Trade name
The trade name is the brand name you trade under, such as the name on your shop board. It need not match the legal name. A proprietor called Ravi Kumar can trade as Kumar Electricals. Changing it is a simple amendment. Keep some proof of the new name, such as a Shop Act certificate or trade licence, in case an officer asks.
After a name change
Download the amended certificate from the portal.
Update invoices, the e-invoice master and bank records.
Tell your regular buyers, so their purchase records show the right name.
Adding or Removing Partners, Directors and the Authorised Signatory
Changes in partners, directors, Karta, trustees or the authorised signatory are filed in REG-14 and, from 1 November 2026, take effect on submission and online validation. The DIN of a director and the PAN of each person are checked by the system.
Partners and directors
Partnership firm: a new partner joining or an old one retiring does not change the firm's PAN, so it is an amendment. Keep the reconstituted deed ready.
Company: add or remove directors after the change is recorded with the Registrar of Companies. Director KYC must be current, or the DIN check can fail.
LLP: add or remove designated partners after the LLP filing is done.
HUF: a change of Karta is also an amendment, as the HUF's PAN stays the same.
Rule 19(5) says these changes apply to all registrations under the same PAN, across all states.
Authorised signatory
The authorised signatory signs returns and applications on the portal. You may add a new signatory, remove one, or change the primary authorised signatory. The REG-14 instructions say a minor cannot be an authorised signatory. You need:
A letter of authorisation signed by the proprietor or partners, or a board resolution for a company
PAN, Aadhaar and a photograph of the new signatory
A working mobile number and email of the new signatory, for OTP verification
If the signatory of a company changes, register the new person's DSC on the portal before the next filing. Rule 26(1) asks companies to verify applications with a DSC.
Shreya GST Expert
Have a question on this topic? Ask Shreya on a free call.
A change in the authorised signatory's mobile number or email takes effect only after OTP verification on the portal, under Rule 19(6) read with Rule 8(2). Bank account details are updated through the same amendment and take effect on submission and validation.
Email and mobile
Log in and open the amendment application for the authorised signatory's details.
Enter the new mobile number and email.
Submit with DSC or EVC.
Complete the OTP verification sent to the new contacts within 3 days.
If you have lost access to the old mobile and email and cannot log in, contact your jurisdictional GST officer in writing. We help you draft this request with proof of identity and authority.
Bank account and Rule 10A
Rule 10A of the CGST Rules asks every new registrant to give valid bank account details within 30 days of registration, or before filing the first GSTR-1 or IFF, whichever is earlier. TDS, TCS and suo moto registrations are outside this rule. The GST Council newsletter of November 2025 says that missing bank details can lead to automatic suspension, with the GSTIN restored once the details are given.
Keep these points in mind:
The account should be in the name of the business. For a proprietorship, the proprietor's own account is used.
Upload a cancelled cheque, the first page of the passbook or a bank statement that shows the name, account number and IFSC.
Delete closed accounts. Refunds go only to an account on your registration.
From 1 December 2026, the new Form GST RFD-01 says bank details in a refund claim must match the registration. Change the bank in REG-14 first.
The documents for a GST amendment are the same documents the law asks for when you first give those details, as the REG-14 instructions say. You upload only the proof that matches the field you change.
Change
Documents to upload
Principal or additional place of business (owned)
Property tax receipt, municipal khata or electricity bill in the owner's name
Rented or leased premises
Valid rent or lease agreement covering the exact address, plus the owner's proof as above
Premises used with consent
Consent letter from the owner, plus the owner's ownership proof
Co-working space
Membership or service agreement with the address
Legal name
Fresh certificate of incorporation, amended deed or other proof of the new name, with the PAN updated
Trade name
Usually none. Keep a Shop Act certificate or trade licence in the new name handy
New partner, director or Karta
PAN, Aadhaar, photograph and address proof of the person. DIN for directors. Updated deed or board resolution
Authorised signatory
Letter of authorisation or board resolution, plus PAN, Aadhaar and photograph of the signatory
Bank account
Cancelled cheque, passbook first page or bank statement
Email or mobile
No upload. Access to the new email and phone for OTP
Goods, services or business activity
No upload in most cases
What officers should not ask for
CBIC Circular No. 257/03/2026-GST dated 26 October 2026 gives a fixed list of registration documents and limits officer queries. Its processing rules are written for new registration applications, but it says the same premises documents apply when you amend a place of business. It tells officers not to ask for an Udyam certificate, not to class an electricity connection as domestic or commercial, and not to treat a home as unfit for business. Bills are checked only for name and address. CBIC circulars are published on the CBIC GST website.
Scans should be clear, complete and in PDF or JPEG format within the portal's size limits. A blurred bill is one of the most common reasons for a query.
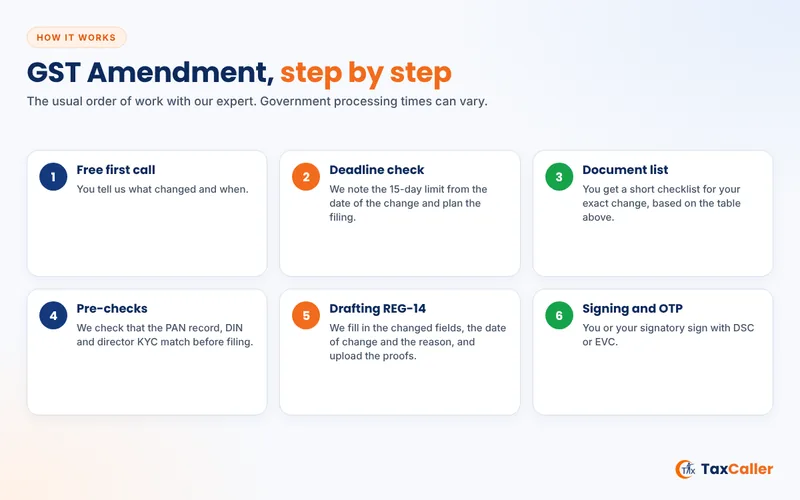
TaxCaller files your GST amendment online in about eight steps, from a first call to the amended certificate. You approve each step, and nothing is filed without your OTP.
Free first call: you tell us what changed and when. We confirm whether it is an amendment, a new registration or a cancellation.
Deadline check: we note the 15-day limit from the date of the change and plan the filing.
Document list: you get a short checklist for your exact change, based on the table above.
Pre-checks: we check that the PAN record, DIN and director KYC match before filing. This avoids failed online validation.
Drafting REG-14: we fill in the changed fields, the date of change and the reason, and upload the proofs.
Signing and OTP: you or your signatory sign with DSC or EVC. Then the primary authorised signatory and one promoter or partner complete OTP verification within 3 days. The ARN is generated only after this.
Follow-up: for a principal place of business change, we track the officer's action. If a REG-03 notice comes, we draft the REG-04 reply within 7 working days.
Handover: you get the ARN, the REG-15 order where one is issued, and the amended certificate. We also give you a list of other records to update.
The portal path for OTP verification is Services, then Registration, then OTP verification of GSTIN, as described in the GSTN advisory of 1 November 2026. Please keep both phones available on the filing day.
Zubair GST Expert
Have a question on this topic? Ask Zubair on a free call.
Most GST amendments now take effect as soon as OTP verification and online checks are done, and the OTP step must be finished within 3 days of submission. A principal place of business change can take up to 15 days, and longer if the officer raises a query.
Stage
Time limit
Rule
File REG-14 after the change
Within 15 days of the change
Rule 19(1)
OTP verification after submission
Within 3 days, or no ARN is generated
REG-14 instructions
Changes other than the principal place of business
Effective on submission and online validation
Rule 19(4)
Officer decision on the principal place of business
Within 15 days of submission
Rule 19(2)(b)
Officer query in REG-03
Within 15 days of submission
Rule 19(2)(c)
Your reply in REG-04
Within 7 working days of the notice
Rule 19(2)(c)
Officer decision after your reply
Within 7 working days of the reply
Rule 19(2)(d)
Officer does not act in time
Certificate treated as amended
Rule 19(2)(g)
Rule 14A principal place change
Effective on submission and validation, from 1 Dec 2026
Rule 19(3)
Bank details for a new registrant
30 days of registration, or before the first GSTR-1 or IFF, whichever is earlier
Rule 10A
Our own work usually takes one working day once your documents are complete. The time after that depends on OTP completion and, for an address change, the officer.
GST Amendment Fees: Government Fee and Our Fee, Clarified
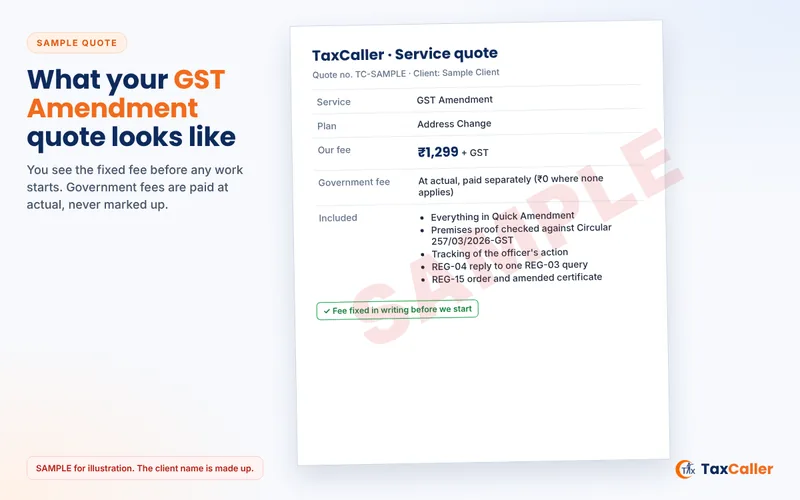
GST Amendment: SAMPLE quote, for illustration only
There is no government fee for a GST amendment. The REG-14 instructions say plainly that no fee is payable for an amendment application. You pay only the professional fee if you use an expert.
TaxCaller's fee
TaxCaller's fee for a GST amendment starts at ₹799 + GST. The final fee depends on the number of changes and whether an officer query needs a reply. We confirm it in writing on the first call, before any work starts.
Item
Paid to
Amount
Review, REG-14 drafting, filing and follow-up
TaxCaller
Starting fee above, quoted in writing, + GST
REG-14 filing fee
Government
Nil
Stamp paper for a rent agreement, consent letter or affidavit, if needed
State (stamp duty)
As per state stamp law, at actual
Name change fee to the ROC or Registrar of Firms, if any
That authority
As per its schedule, at actual
Penalty for late filing, if ever levied
Government
As per the order, at actual
Government fees and stamp duty are never part of our invoice. You pay them directly to the authority concerned. Our fee is + GST because our service is itself a taxable supply.
Why Updating on Time Matters: Benefits and Penalties
Filing REG-14 on time keeps your GSTIN, notices, e-way bills and refunds working, while a missed amendment can attract a penalty of up to ₹25,000 under Section 125 of the CGST Act. There is no separate late fee for REG-14.
Benefits of a timely amendment
Notices reach you: officers serve notices on the portal and at the registered address and email.
Verification visits go smoothly: the officer finds you at the address on record.
Refunds go to the right account: refunds are paid only to a bank account on the registration.
Clean e-way bills: dispatch addresses match your registered places of business.
Buyer trust: buyers who check your GSTIN see the correct name and address.
Easier loans and tenders: banks and tender bodies often match the GST certificate with other records.
What can go wrong if you do not amend
Risk
Provision
General penalty for a breach with no specific penalty, up to ₹25,000
Section 125, CGST Act
Suspension and show cause notice for cancellation if you are not found at the registered address
Section 29(2) and Rule 21A
Automatic suspension if bank details are missing
Rule 10A, GSTN advisory of November 2025
Goods at an undeclared godown questioned during inspection
Section 67 (inspection, search and seizure)
Refund claim held up if bank details do not match
Form GST RFD-01, from 1 Dec 2026
The 57th GST Council meeting on 8 October 2026 recommended cutting the Section 125 general penalty from ₹25,000 to ₹10,000. That is a recommendation and needs a change in the law. Until then, ₹25,000 applies.
Abhinay Rai GST Expert
Have a question on this topic? Ask Abhinay on a free call.
Most GST amendment rejections come from address proof that does not match, unclear documents, unanswered queries and failed online checks. Each one can be avoided with a careful review before filing.
Reasons we see most often
Address mismatch: the address typed in REG-14 differs from the bill or agreement. Circular 257/03/2026-GST lists this as one of the few grounds on which an officer may raise a query on a registration application.
Vague address: no building number, floor or landmark.
Unclear scans: blurred, cut or partial documents.
Weak rent papers: an expired agreement, wrong names, or a property not covered by the agreement.
Consent letter without owner proof: the consent letter alone is not enough.
No reply to REG-03: missing the 7 working day window leads to deemed rejection in REG-05A.
OTP not done in 3 days: no ARN is generated, and you must file again.
PAN, DIN or CIN mismatch: the legal name was not changed in the PAN first, or a director's KYC is not current.
Wrong route: trying to change the state or PAN through REG-14.
Address change during suspension: the portal does not allow a principal place of business change while the GSTIN is suspended.
Other mistakes that cost time
Filing after the 15-day limit without a reason on record
Entering a wrong date of change
Forgetting to delete a closed branch or old bank account
Not updating the e-invoice and e-way bill masters after approval
If your application is rejected
You can file a fresh REG-14 with the right documents. You can also appeal against a rejection order under Section 107 of the CGST Act within three months. For a notice that needs a detailed reply, see our GST notice reply service.
A GST amendment is verified by OTP on the mobile and email of the primary authorised signatory and one promoter or partner, not by biometric Aadhaar authentication. The new Rule 19 does not add a biometric step for REG-14.
What the REG-14 instructions require
Mobile and email verification of the primary authorised signatory and one selected promoter, partner, director, Karta, member or trustee.
For TDS, TCS, non-resident and UIN registrations, verification of the authorised signatory's mobile and email.
All OTP steps within 3 days of submission. If they fail or are not done, the ARN is not generated.
Online checks of PAN against Income Tax records, and of DIN and CIN where they apply.
Where Aadhaar and biometrics do apply
Situation
Verification
New registration in REG-01, applicant selected on risk parameters
Biometric Aadhaar authentication and photograph at a GST Suvidha Kendra, under Rule 8(4A) of the CGST Rules
New registration under Rule 14A
Aadhaar authentication of the primary authorised signatory and at least one promoter or partner
Withdrawal from Rule 14A or 14B in REG-32
OTP or biometric Aadhaar authentication of the primary authorised signatory and one promoter or partner
Amendment in REG-14
OTP on mobile and email, plus online validation
Practical tip: the OTP goes to the contact details on record. If a partner has changed their number, update it first, or the 3-day window may run out.
Worked Example: A Firm That Moves, Adds a Godown and a Partner
This example shows how one business handles three changes under the 2026 rules. The names are made up, but the steps follow the rules above.
The facts: Mehta Traders is a partnership firm registered in Uttar Pradesh. On 1 December 2026 it moves its office from Ghaziabad to Noida. On the same day it rents a godown in Noida and admits a new partner. It also opens a new current account. The firm's PAN does not change.
Change
Route
Effect
Office moves to Noida (same state)
Principal place of business, officer route
From the date the officer approves, or deemed amended
Godown in Noida
Additional place of business
On submission and online validation
New partner joins
Partners
On submission and online validation
New current account
Bank details
On submission and online validation
The dates:
Last date to file REG-14: 16 December 2026, which is 15 days from the change.
TaxCaller files on 8 December 2026, after checking the new rent agreement and the partner's PAN.
The primary authorised signatory and one partner finish OTP verification by 11 December 2026. The ARN is generated.
The officer has 15 days from 8 December, so until 23 December 2026, to approve the office change or raise a REG-03 query.
Say a REG-03 query comes on 18 December asking for a clearer electricity bill. The firm replies in REG-04 within 7 working days. The officer then has 7 working days to decide.
The lesson: the godown, partner and bank changes are live within days. Only the office address waits for the officer. Filing a week before the 16 December deadline put the office change before the officer sooner, so the query was settled earlier.
Shadab GST Expert
Have a question on this topic? Ask Shadab on a free call.
Correcting a GST return is not done through REG-14. Return errors are fixed in later returns, within the time limits in the CGST Act. This page covers registration changes, so here is only a short guide.
GSTR-1: fix a mistake in GSTR-1A before filing GSTR-3B for the same period, or in the amendment tables of a later GSTR-1.
GSTR-3B: it cannot be revised. Short or excess tax is adjusted in a later GSTR-3B.
Time limit: corrections for a financial year must be made by 30 November of the next year, or the date of filing the annual return if earlier (Sections 37(3) and 39(9)).
What Changed for GST Registration Amendments in 2026
The biggest 2026 change is the new Rule 19, in force from 1 November 2026, which lets most registration changes take effect on submission and keeps officer approval only for the principal place of business. Here is the full list, with sources.
Rule 19 substituted (1 November 2026): Notification 05/2026-Central Tax, G.S.R. 919(E), dated 26 October 2026, replaced Rule 19. Legal name, partners, directors and additional places of business no longer need an officer.
Officer time limit: for the principal place of business, the officer now has 15 days from submission. The old rule allowed 15 working days.
New REG-05A: if you do not answer a REG-03 query in time, the application is deemed rejected and the portal issues REG-05A.
New Form REG-14 (replaced from 1 November 2026): OTP verification by the primary authorised signatory and one promoter or partner within 3 days, and online checks of PAN, DIN and CIN before an ARN is generated. The form also says that no fee is payable.
GSTN advisory of 1 November 2026: GSTN put the new process live on the portal and explained the OTP route, as reported by several tax publications.
Rule 14A registrants (1 December 2026): a change in principal place of business by a Rule 14A registrant takes effect on submission and validation, under Rule 19(3).
Circular 257/03/2026-GST (26 October 2026): a fixed document list and a closed list of queries for registration applications.
New Form RFD-01 (1 December 2026): bank details in a refund claim must match the registration.
Coming on 1 April 2027: Rule 21A system-based suspension, with Form REG-31 asking for valid bank details under Rule 10A within 30 days.
Late 2025 changes still relevant: GSTN's advisory of 20 November 2025 announced automatic suspension where Rule 10A bank details are missing. The simplified Rule 14A registration also came in during November 2025, through Notification 18/2025-Central Tax.
Recommended, not yet law: the 57th GST Council meeting proposed a lower Section 125 penalty. Check the GST portal (gst.gov.in) for the current position before filing.
After a GST amendment is approved, download the new certificate and update every record that carries your GST details. This short checklist covers the usual ones.
Download the amended registration certificate and display it at each place of business.
Update invoices, quotations, letterheads and your accounting software.
Check that the e-invoice and e-way bill portals show the new details.
Tell your main buyers and suppliers about a new name or address.
Update other registrations that show your address, such as Shop Act, trade licence or IEC.
Keep the REG-14 copy, ARN and any REG-15 order with your records.
How We Help After Approval
TaxCaller has handled tax and compliance work since 2018, from our office in Ghaziabad and online across India. This page was reviewed by Abhinay Rai, Advocate.
We check whether you need an amendment, a new GSTIN or a cancellation before you file.
We check the PAN, DIN and documents first, so online validation does not fail.
Our fee is quoted upfront, and there is no government fee to add.
One expert tracks your case until the change is live.
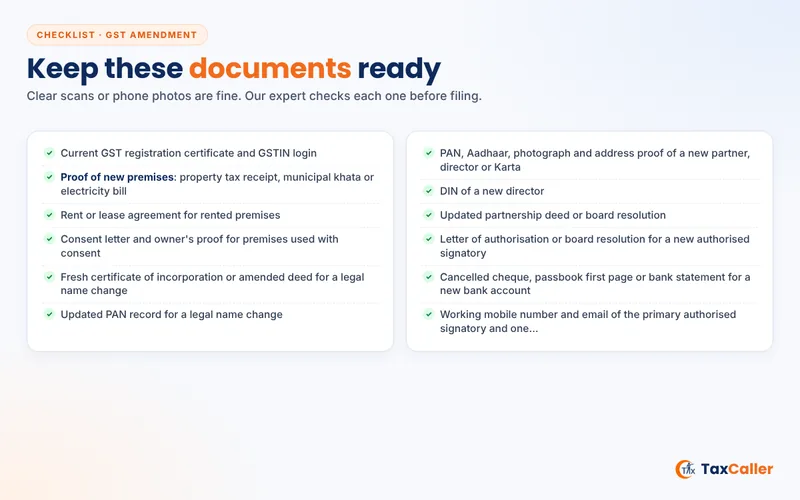
Current GST registration certificate and GSTIN login
Proof of new premises: property tax receipt, municipal khata or electricity bill
Rent or lease agreement for rented premises
Consent letter and owner's proof for premises used with consent
Fresh certificate of incorporation or amended deed for a legal name change
Updated PAN record for a legal name change
PAN, Aadhaar, photograph and address proof of a new partner, director or Karta
DIN of a new director
Updated partnership deed or board resolution
Letter of authorisation or board resolution for a new authorised signatory
Cancelled cheque, passbook first page or bank statement for a new bank account
Working mobile number and email of the primary authorised signatory and one promoter for OTP
DSC of the signatory for companies
Why TaxCaller
Real experts, not a call centre
Your work is handled by experienced professionals who explain every step, check your documents and keep you updated.
Registered company
TaxCaller is run by TaxCaller India LLP (LLPIN AAQ-7388), serving clients since 2018.
Fee told upfront
You know the complete fee, our professional fee and the government fee, before any work starts. No hidden charges.
Support after the work
Notices, renewals, returns and compliance reminders: we stay with your business after the registration is done.
Reviewed By
Expert for this topic GST Amendment
Abhinay Rai
Advocate
Abhinay Rai is a Advocate specialising in GST Amendment. The process, documents, timelines and fees on this page are checked against the current rules and government portals, and updated whenever the law, forms or fees change.
GST amendment means changing details in your existing GST registration, such as address, partners, signatory, name or bank account. It is filed online in Form GST REG-14 under Section 28 of the CGST Act and Rule 19 of the CGST Rules. Your GSTIN stays the same. Only the details behind it change, and the certificate is updated.
What is the time limit for GST amendment?
You must file Form GST REG-14 within 15 days of the date on which the change happens, under Rule 19(1). The clock runs from the event, such as the date you shift office or a partner joins. After filing, OTP verification must be completed within 3 days, or no ARN is generated and you must file again.
Is there any government fee for GST amendment?
No. The instructions to Form GST REG-14 say that no fee is payable for an amendment application. You may still pay stamp duty on a rent agreement or consent letter, or a fee to the ROC for a company name change. TaxCaller's professional fee is separate, quoted upfront and charged + GST.
What is the difference between core and non-core fields in GST?
Core fields needed officer approval, while non-core fields updated on filing. Until 31 October 2026, core fields were legal name, places of business and partners or directors. From 1 November 2026, the new Rule 19 keeps officer approval only for the principal place of business. Other changes take effect on submission and online validation.
How long does GST amendment approval take?
Most changes take effect once OTP verification and online checks are complete, and OTP must be done within 3 days of submission. A principal place of business change goes to the officer, who must act within 15 days of submission. If a REG-03 query is raised, you reply within 7 working days and the officer decides within 7 working days.
Can I change the PAN in my GST registration?
No. The PAN is part of the GSTIN and cannot be changed through REG-14. Rule 19(7) says that if a change in constitution gives you a new PAN, you must apply for fresh registration. Examples include a proprietorship becoming a partnership or a firm converting into an LLP. The old GSTIN is then cancelled.
Can I shift my GST registration to another state?
No. GST registration is state-wise under Section 25(1), so a GSTIN cannot move across states. If your business moves, register afresh in the new state and cancel the old GSTIN if no business remains there. If both places continue, keep both registrations. Moving within the same state is an amendment of principal place of business.
How do I change the business address in GST registration?
File REG-14 to amend the principal place of business, with proof of the new premises such as a property tax receipt, electricity bill, rent agreement or consent letter. Complete OTP verification within 3 days. The officer approves in REG-15 within 15 days of submission, and the change takes effect from the date of approval.
How do I change the email or mobile number in GST?
Update the authorised signatory's contact details through REG-14 and sign with DSC or EVC. The change takes effect only after OTP verification on the portal, under Rule 19(6) read with Rule 8(2). If you have lost access to the old email and mobile and cannot log in, write to your jurisdictional GST officer for help.
How do I add a warehouse or branch to my GST registration?
Add it as an additional place of business in REG-14, with proof of the premises. It must be in the same state as your GSTIN. Since 1 November 2026 it takes effect on submission and online validation, without officer approval. A warehouse in another state needs a separate GST registration in that state.
What happens if the officer does not act on my amendment?
Under Rule 19(2)(g), if the officer does not approve, reject or raise a query within the time limit, the certificate is treated as amended. For a principal place of business change, the limit is 15 days from submission, or 7 working days from your reply to a REG-03 notice. The amended certificate then appears on the portal.
What if my GST amendment application is rejected?
The officer must give reasons in Form GST REG-05. If you missed a query deadline, the portal issues REG-05A. You can file a fresh REG-14 with correct documents, which is often quicker. You can also appeal the rejection order under Section 107 of the CGST Act within three months. We help with both routes.
Can I amend a GST return after filing it?
Yes, but not through REG-14. GSTR-1 errors are fixed in GSTR-1A or in a later GSTR-1, and GSTR-3B errors are adjusted in a later GSTR-3B. Corrections for a year must be made by 30 November of the next year, or the annual return date if earlier, under Sections 37(3) and 39(9).
Do I need biometric Aadhaar verification for GST amendment?
No. The new Rule 19 and Form REG-14 rely on OTP verification of the mobile and email of the primary authorised signatory and one promoter or partner. Biometric Aadhaar authentication at a GST Suvidha Kendra applies to some new registration applicants under Rule 8(4A). Aadhaar authentication is also needed for Rule 14A registration and for withdrawal in REG-32.
Get your GST registration details updated the right way
Tell us what changed and when, and our expert will file your REG-14 online before the 15-day limit. Our fee starts at ₹799 + GST, and there is no government fee.