Starting from · ₹799 GST Consultant Expert Call plan
STARTING FROM₹799
FEE TOLD UPFRONTFree first call
!Late GST return?Late fee and interest run till you file
Since 2018Trusted Experience
980+Experts Connected
220+Cities Served
1164+Agents Available
12000+Founders Trusted
S
Srishti Magoo
★★★★★
Excellent experience with TaxCaller for filing my &
my family members ITR returns. The entire process was
smooth, quick and hassle-free. They are professional,
knowledgeable and guided me through every step with patience.
O
obeid sait
★★★★★
The team has handled my taxes for the past three years,
and it's been a wonderful, hassle-free experience.
Thank you for your consistently quick and efficient service.
P
Pushkar
★★★★★
They are among the best in their field. Their work culture
is highly professional, and their client service is smooth
and reliable. They can confidently be relied on to get the job done.
P
Prasad Sheth
★★★★★
Excellent experience with TaxCaller! The ITR filing
process was smooth, quick, and completely hassle-free.
The CA was knowledgeable, responsive, and explained everything clearly.
A
Apoorv Bansal
★★★★★
Excellent service for ITR filing. The team was highly
professional, responsive, and guided me through the entire
process smoothly. My return was filed accurately and on time.
A
Abhishek Kumar
★★★★★
I was searching for a good CA firm in Ghaziabad and found
TaxCaller. The experience was excellent from start to finish.
The team is responsive, transparent, and genuinely helpful.
U
uma pandey
★★★★★
Great service! TaxCaller India made the entire ITR filing
process quick, smooth, and hassle-free. They answered all
my queries patiently and ensured maximum accuracy.
T
tanu mittal
★★★★★
Excellent job! We've been connected for many years,
and your success truly makes me happy. You are an
incredibly intelligent person. Keep shining, keep growing.
B
Bhanu Pratap Maurya
★★★★★
I am filing my ITR since past 3 years with Abhinav and
Firm is known as TaxCaller and they are professional
interms of ITR rules. They will explain and tell you all
the information.
A
ashish Sharma
★★★★★
I am providing my honest reviews:
No.1 service ...
A
AARYAN GROUP
★★★★★
Honestly, finding a good CA firm in Ghaziabad was
confusing, but TaxCaller India made it simple.
I contacted them for GST work and the experience was smooth.
N
News Speaks
★★★★★
If you're looking for a reliable CA firm in Ghaziabad,
TaxCaller India is a great choice. They provide complete
taxation and compliance solutions including GST.
A
Anshul Chaprana
★★★★★
Got my GST registration done through TaxCaller CA firm.
Process was quite smooth, they guided properly on documents
and didn't waste time. Overall good experience.
How we work
Online · Call · WhatsApp
Quick answer
A GST consultant is a tax expert who handles your ongoing GST work, such as notices, replies, appeals, refunds, ITC matching and advice. TaxCaller's experts read your notice, check the law and your data, draft the reply and track every deadline. The first call is free. Our fee is confirmed before work starts and is charged + GST.
Government fees and taxes are extra where applicable. Our expert confirms the final amount on the first call. No hidden charges.
About GST Consultant Services
A GST consultant is the person you call when GST stops being routine. A notice arrives on the portal. Your input tax credit does not match GSTR-2B. A refund is stuck. An officer wants records for an audit. TaxCaller gives you a tax expert who studies the problem, explains it in plain words and does the paperwork with you.
This page is about that ongoing help. If you only need a new GSTIN, see our GST registration page. If you only need monthly or quarterly returns filed, see GST return filing. Here we cover notices, replies, appeals, refunds, reconciliation, LUT, e-invoice and e-way bill questions, audit support and advice.
Every legal point on this page is checked against the Central Goods and Services Tax Act, 2017 (CGST Act), the CGST Rules, 2017 and official CBIC and GST Council releases, as they stand in November 2026. The page is reviewed by Abhinay Rai, Advocate.
Complete guide
Choose a topic to open it. Every answer gives the rule or section it comes from.
01 Topic 1 of 20
What a GST Consultant Does
GST is a self-assessed tax. You decide your own tax, file your own returns and claim your own credit. The department checks later. That check can come years after the return. A GST consultant helps you get the first filing right and defend it when the department asks questions.
In practical terms, our experts do five kinds of work:
Disputes: reading notices, drafting replies, preparing for personal hearings and filing appeals.
Money back: refund claims for exports, inverted duty and excess cash balance.
Credit control: matching your purchase register with GSTR-2B and fixing gaps before they become demands.
Advice: tax rates, HSN or SAC codes, place of supply, reverse charge, contracts and invoices.
Checks: health checks, annual return review and support during audits.
A consultant does not replace your accountant. Your accountant keeps the books. The consultant reads the law against those books and tells you where the risk sits.
Any registered person can face a GST question. Some moments make expert help sensible rather than optional:
You receive a notice in FORM GST ASMT-10, DRC-01A, DRC-01, ADT-01 or a summons.
Your registration is suspended or cancelled, or a physical verification is due.
You export goods or services and need a LUT or a refund.
Your credit in GSTR-3B is higher than GSTR-2B shows, and the portal flags it.
You cross ₹5 crore turnover and must start e-invoicing.
You sign a large contract and are unsure of the rate, place of supply or reverse charge.
An order has gone against you and the appeal clock has started.
We work with traders, manufacturers, exporters, e-commerce sellers, IT and service firms, contractors, restaurants, clinics and startups. Each sector has its own GST traps. A contractor worries about works contract rates. An exporter worries about refunds. A seller on a marketplace worries about TCS and stock in other states.
What you gain: fewer missed deadlines, credit claimed only where the law allows it, replies that answer the actual charge, and a written record of every step. You also get time back. Your team runs the business while the expert handles the department.
Abhinay Rai GST Expert
Have a question on this topic? Ask Abhinay on a free call.
GST Notices: ASMT-10, DRC-01 and Sections 73, 74 and 74A
Not every notice is a demand. The form number tells you how serious it is. Read it first, then act.
Notice
What it means
Your reply
ASMT-10
Scrutiny of returns under Section 61 and Rule 99. The officer found a discrepancy.
ASMT-11 within 30 days of service. If accepted, the officer issues ASMT-12.
DRC-01A
Pre-notice intimation of tax the officer thinks is due
Pay through DRC-03 or file objections in Part B
DRC-01
Summary of a show cause notice (SCN) under Section 73, 74 or 74A
DRC-06 by the date given in the notice
DRC-01B
Liability in GSTR-1 is higher than in GSTR-3B (Rule 88C)
Pay the gap or explain it in Part B
DRC-01C
Credit in GSTR-3B is higher than in GSTR-2B (Rule 88D)
Reverse the excess or explain it
ADT-01
Departmental audit under Section 65
Keep records ready for the audit date
REG-17 / REG-31
Show cause for cancellation or suspension of registration
REG-18 reply to REG-17; reply to REG-31 within 30 days (Rule 21A). Attach returns and proof
Which section applies? The Finance (No. 2) Act, 2024 split demand cases by year. Sections 73 and 74 now apply to tax up to Financial Year 2023-24. Section 74A applies to tax for Financial Year 2024-25 onwards.
Point
Section 73 (up to FY 2023-24)
Section 74 (up to FY 2023-24)
Section 74A (FY 2024-25 onwards)
Type of case
No fraud or suppression
Fraud, wilful misstatement or suppression
Both, in one section
Time for order
3 years from annual return due date
5 years from annual return due date
Notice within 42 months of annual return due date; order within 12 months of notice
Penalty
10% of tax or ₹10,000, whichever is higher
Equal to tax
10% or ₹10,000 (non-fraud); equal to tax (fraud)
Early payment relief
No penalty if paid with interest within 30 days of SCN
15% before SCN, 25% within 30 days of SCN, 50% within 30 days of order
Non-fraud: no penalty within 60 days of SCN. Fraud: 15%, 25% or 50% with 60-day windows
Under Section 74A(1), no notice is issued if the unpaid tax for a year is below ₹1,000. Check the section quoted in your notice. A notice for FY 2024-25 that quotes Section 73 or 74 instead of Section 74A can be questioned on that point. You can read the current text of each section on the CBIC GST website.
If an order goes against you, the law gives you three levels of appeal. Each has a strict clock.
First appeal (Section 107): file FORM GST APL-01 online within 3 months of the date the order is communicated. For sufficient cause, the Appellate Authority can allow one more month. You must pay the admitted amount in full and 10% of the disputed tax, capped at ₹20 crore under the CGST Act (the cap was cut from ₹25 crore by the Finance (No. 2) Act, 2024). The authority should try to decide within one year.
Tribunal appeal (Section 112): appeal to the GST Appellate Tribunal (GSTAT) within 3 months of the first appeal order. The tribunal can admit a late appeal within 3 more months for sufficient cause. Pre-deposit is a further 10% of the remaining disputed tax, capped at ₹20 crore. For penalty-only orders, 10% of the penalty applies.
High Court (Section 117): an appeal lies only on a substantial question of law, within 180 days of the tribunal order.
GSTAT status in 2026: the tribunal was launched on 24 September 2025, with a Principal Bench in New Delhi and 31 State Benches at 45 locations (PIB release on the GSTAT launch). Appeals are filed online on the GSTAT e-filing portal. The window for backlog appeals was first set at 30 June 2026. On 30 June 2026 it was extended to 31 July 2026 for orders communicated before 1 May 2026. For orders communicated on or after 1 May 2026, the normal 3-month limit under Section 112(1) applies. That backlog window has now closed, so any new tribunal appeal must meet the 3-month rule.
A good appeal is built at the reply stage. Facts and documents you never placed before the officer are hard to bring in later. That is why we treat every SCN reply as if it will be read by the tribunal.
Shadab GST Expert
Have a question on this topic? Ask Shadab on a free call.
Refund claims fail more often on paperwork than on law. We check eligibility first, then build the claim.
Who can claim: exporters of goods or services under LUT, suppliers to SEZ units, businesses with an inverted duty structure, and anyone with excess balance in the electronic cash ledger.
Form and time limit: FORM GST RFD-01 on the portal, within 2 years from the relevant date (Section 54(1) and Rule 89).
Provisional refund: for zero-rated supplies, 90% can be released provisionally under Section 54(6). From 1 November 2026, this also covers inverted duty refunds.
Interest on delay: if the refund is not paid within 60 days of a complete application, interest is due under Section 56 at the notified rate, which the Act caps at 6% a year. Where the refund flows from an appeal or court order, the cap is 9%.
Embassies and UN bodies: holders of a Unique Identity Number claim refunds of tax paid on purchases under Section 55, through their own refund form.
LUT: to export without paying IGST, file a Letter of Undertaking in FORM GST RFD-11 under Rule 96A before you export. It is filed online for each financial year. There is no government fee. If goods are not exported within the allowed time, tax with interest becomes payable. Most exporters should file the LUT in early April so the new year starts clean.
Input tax credit (ITC) is where most GST demands begin. The law sets several conditions:
The supplier must have reported the invoice, so that it shows in your GSTR-2B (Section 16(2)(aa)).
You must have received the goods or services, and the supplier must have paid the tax.
Credit must be claimed by 30 November after the end of the financial year, or the annual return date if earlier (Section 16(4)).
If you do not pay the supplier within 180 days, the credit is reversed under Rule 37.
If the supplier has not filed GSTR-3B for the period, Rule 37A asks you to reverse the credit until the supplier files.
Blocked credits under Section 17(5), such as most motor vehicle and personal-use items, cannot be claimed at all.
Our monthly reconciliation compares your purchase register with GSTR-2B and the Invoice Management System (IMS). We list missing invoices, wrong GSTINs, duplicate claims and suppliers who have not filed. You get a short action list, not a long report.
GST health check: once a year, we review your GSTR-1, GSTR-3B, GSTR-2B, e-way bills and books together. We look for the gaps that trigger ASMT-10, DRC-01B and DRC-01C. Finding them yourself costs a correction. Having the officer find them costs interest and possibly a penalty.
Many disputes start with a single wrong decision on an invoice. Advice before the sale is cheaper than a reply after the notice.
Rates and classification: the right HSN or SAC code and rate. Rates were restructured into mainly 5% and 18%, with a 40% rate for a few goods and services, from 22 September 2025 (PIB release on the 56th GST Council meeting).
Place and time of supply: whether a sale is intra-state or inter-state, and when tax is due.
Reverse charge: services such as legal fees and goods transport where the buyer pays the tax.
Contracts: how GST clauses, discounts, advances and cross-charges between branches should be written.
Price changes: passing on rate cuts to buyers, as Section 171 expects.
Advance ruling: help to decide whether a binding ruling under Section 97 is worth seeking.
E-invoice: businesses whose aggregate turnover in a financial year has crossed ₹5 crore must issue e-invoices for B2B supplies (Rule 48(4), Notification 10/2023-Central Tax, from 1 August 2023). We help you set up the flow, report invoices on time and fix rejected invoices.
E-way bill: needed under Rule 138 when goods worth more than ₹50,000 move. We advise on Part A and Part B, validity, transport changes and what to do if goods are detained.
Customs duty is a separate law. If your issue is mainly customs, we tell you so on the first call.
Shreya GST Expert
Have a question on this topic? Ask Shreya on a free call.
The department can examine your records in several ways. Each has its own rules.
Scrutiny (Section 61): a desk check of returns. It leads to ASMT-10 if the officer sees a gap.
Departmental audit (Section 65): you get FORM GST ADT-01 at least 15 working days before the audit. The audit should finish within 3 months, extendable by up to 6 months. Findings come in ADT-02.
Special audit (Section 66): ordered when value or credit looks abnormal. A chartered or cost accountant nominated by the Commissioner examines your books. The report is due in 90 days, extendable by 90 more.
Inspection and search (Section 67): authorised officers can inspect premises and records.
Summons (Section 70): you may be called to give evidence or produce documents.
We prepare reconciliations that auditors ask for: turnover in books vs GSTR-1, tax paid vs GSTR-3B, and credit in books vs GSTR-2B. We also review your GSTR-9 and GSTR-9C before filing, because the annual return is the base date for the limitation period in Sections 73, 74 and 74A.
Under CBIC Circular 122/41/2019-GST, summons, search authorisations, inspection notices and enquiry letters from central tax officers must quote a Document Identification Number (DIN). Without one, they are treated as invalid unless a listed exception applies. We check that too.
Knowing the limits helps you hire well and avoid people who promise too much.
A consultant can:
Prepare returns, statements, refund claims and replies for you.
As an enrolled GST practitioner under Section 48 and Rule 83, file returns, refund claims and registration changes once you authorise them on the portal.
Appear before an officer, the Appellate Authority or the tribunal as your authorised representative, if they fall in a category under Section 116(2). These are a relative or regular employee, an advocate, a practising chartered accountant, cost accountant or company secretary, a qualified retired officer, or an enrolled GST practitioner.
Explain your options, including when paying early is cheaper than fighting.
A consultant cannot:
Take over your legal responsibility. Under Section 48(3), the registered person stays responsible for what is filed.
File without your approval. You confirm practitioner filings by email or SMS (Rule 83), and returns are verified with your EVC or DSC.
Appear for you where the law needs you in person, such as examination on oath.
Argue a writ or appeal in the High Court unless they are an advocate.
Promise that a demand will be dropped. Outcomes depend on facts, records and the officer.
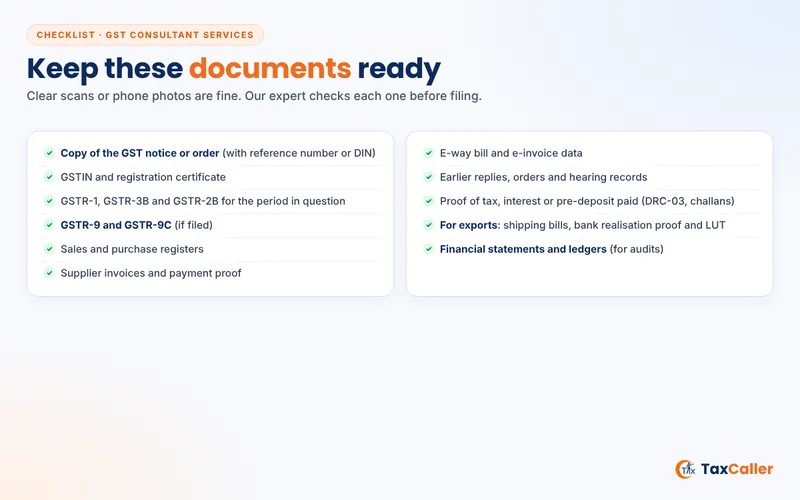
Use this checklist before you hire anyone, including us:
Check standing. Ask whether they are an enrolled GST practitioner, an advocate, or a practising CA, CS or CMA. Ask who will appear if a hearing is needed.
Ask about similar cases. A refund for an exporter is different from a fraud SCN. Ask what they have handled before.
Get the scope in writing. Reply only, or reply plus hearing? First appeal included or not?
Get the fee in writing. It should show the professional fee, GST on it, and government payments separately.
Check how they protect data. A good consultant does not need your portal password if you can engage them as a practitioner on the portal.
Test response time. Notices have short deadlines. Ask how fast they reply on working days.
Watch for red flags. Anyone who promises a result, suggests fake invoices or asks you to backdate documents puts you at risk under Section 122 and Section 132.
You can check the enrolment of a GST practitioner by searching on the GST portal.
Zubair GST Expert
Have a question on this topic? Ask Zubair on a free call.
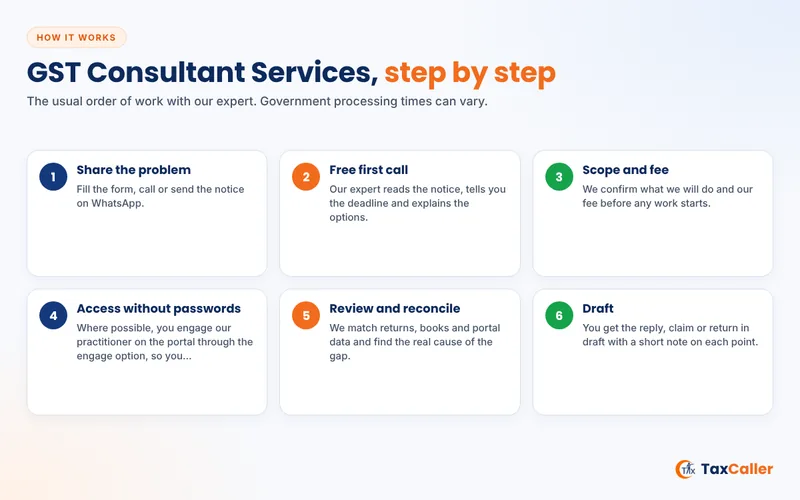
Our turnaround: we aim to share a first view on a notice within one working day of receiving it. Draft time depends on data size and is agreed on the first call. Send notices early. A reply drafted in the last two days is rarely the strongest one.
Abhinay Rai GST Expert
Have a question on this topic? Ask Abhinay on a free call.
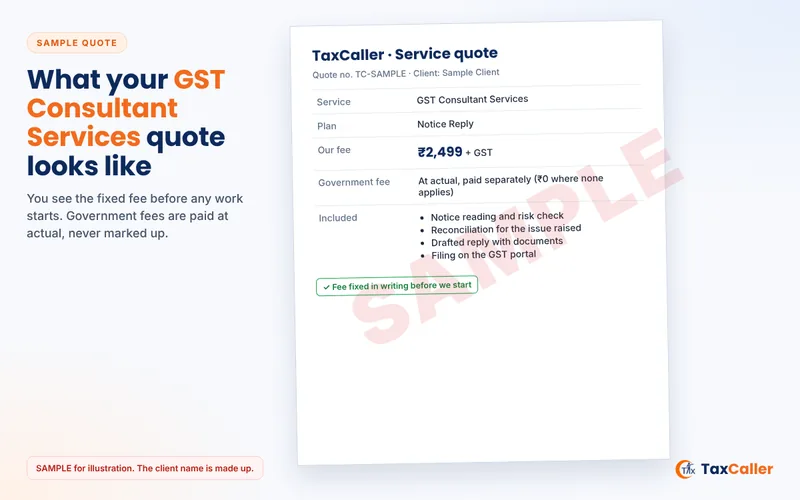
GST Consultant Services: SAMPLE quote, for illustration only
Two kinds of money are involved in GST work. Keep them apart.
1. Payments to the government (paid by you, directly, at actual):
Filing a reply, refund claim or LUT on the portal: no government fee.
First appeal: no filing fee, but a pre-deposit of 10% of disputed tax under Section 107(6).
Tribunal appeal: a further 10% pre-deposit under Section 112(8), plus the filing fee prescribed under Rule 110(5), which is capped at ₹25,000.
Advance ruling: ₹5,000 under Rule 104 of the CGST Rules, plus the fee under the State GST law.
Any tax, interest, late fee or penalty that is actually due.
Pre-deposit is not a cost if you win. It is refunded with interest.
2. TaxCaller's professional fee: the fee depends on the task. A single ASMT-10 reply is different from a fraud SCN with a hearing. Our fees start at ₹799 + GST for an expert call, ₹2,499 + GST for a notice reply and ₹4,999 + GST a month for ongoing support. Our expert confirms the exact scope on the first call, before any work starts. TaxCaller's fee is charged + GST. Government fees, pre-deposits, tax, interest and penalties are paid separately at actual and are never part of our fee.
For a quick tax estimate before the call, try our free tax tools.
Late fee per day, reduced by notification (for GSTR-3B, Notification 19/2021-Central Tax), with lower caps for nil returns and caps linked to turnover
Section 47
Late annual return
Late fee per day, capped as a share of turnover
Section 47(2)
Late tax payment
Interest at the notified rate, which the Act caps at 18% a year
Section 50(1)
Wrong ITC used
Interest at the rate notified under Section 50(3)
Section 50(3)
Short tax, no fraud
10% of tax or ₹10,000, whichever is higher
Sections 73, 74A
Short tax, with fraud
Penalty equal to tax
Sections 74, 74A
Specified offences (fake invoices, wrong ITC, not registering)
₹10,000 or tax evaded, whichever is higher
Section 122(1)
Other breaches with no set penalty
Up to ₹25,000
Section 125
Goods moved without e-way bill
Detention and penalty
Section 129
Interest is automatic. Penalty depends on the section and on how fast you act. Paying tax and interest early, where the demand is clearly correct, often cuts the penalty to nil or a small share.
Not checking the portal. Notices are served on the GST portal and by email. Many businesses learn of a demand only when their bank account is attached.
Missing the reply date. An order passed without your reply is much harder to fight.
Replying with opinions, not evidence. Officers act on reconciliations and documents.
Ignoring the section number. A notice under the wrong section or out of time can fail on that point.
Skipping the personal hearing. Section 75(4) gives you a right to be heard before an adverse order. Use it.
Claiming credit from non-filers. Credit not in GSTR-2B is the top reason for DRC-01C.
Filing an appeal without pre-deposit. The appeal cannot proceed until it is paid.
Paying under protest without recording it. Use DRC-03 with a clear note, so the payment is linked to the case.
Letting returns age. Returns older than 3 years from the due date can no longer be filed on the portal.
Shadab GST Expert
Have a question on this topic? Ask Shadab on a free call.
These are the 2026 changes that matter most for notices, appeals and refunds:
GSTAT is running. After its launch in September 2025, the tribunal took backlog appeals until 31 July 2026 (extended from 30 June 2026 by a notification of 30 June 2026 under Section 112). New appeals now follow the 3-month limit. See Section 112 on the CBIC tax information portal.
Finance Act, 2026 changes in force from 1 November 2026 (Notification 03/2026-Central Tax, 26 October 2026):
Post-sale discounts: under amended Section 15(3)(b) and Section 34(1), a discount can be kept out of value if a credit note is issued and the buyer reverses the matching ITC. A prior agreement is no longer needed.
Provisional refunds under Section 54(6) now also cover inverted duty structure refunds.
Section 54(14) no longer blocks small refund claims for goods exported on payment of tax.
Faster refund processing. From 1 November 2026, the CGST (Amendment) Rules, 2026 (Notification 05/2026-Central Tax, 26 October 2026) cut the refund acknowledgement period under Rule 90 from 15 to 10 days. If the officer does not act in time, the claim is deemed acknowledged. For inverted duty refunds under Rule 89(5), ITC on input services availed on or after 1 November 2026 now counts. Both changes follow the 57th GST Council's recommendations (PIB release on the 57th GST Council reforms).
Section 74A cases are now live. Section 74A covers tax for FY 2024-25 onwards. Demands for those years follow Section 74A, not Sections 73 or 74.
Proposals not yet law. The 57th GST Council, meeting on 8 October 2026, recommended no SCN where tax is under ₹10,000, a 5% penalty for quick payment after an order, a lower general penalty of ₹10,000 and tighter rules for e-way bill interception. These are recommendations only. They apply once Parliament or the government notifies them, and we will update this page when they do.
Rule 86A hearing, from April 2027. A new procedure lets you object to blocked credit and be heard before the officer decides. It has been notified in the same CGST (Amendment) Rules, 2026, but starts only on 1 April 2027.
Why TaxCaller, from Ghaziabad to Anywhere in India
Serving clients since 2018. TaxCaller India LLP (LLPIN AAQ-7388) works from Ghaziabad and online across India.
Reviewed content. Our GST pages are reviewed by Abhinay Rai, Advocate.
Fee before work. You know our fee, and what the government will collect, before we start.
You stay in control. Nothing is filed without your approval.
Plain language. We explain the notice in simple words, in English or Hindi.
State and city note: GST is administered by both the Centre and the states. Your registration certificate shows whether you fall under central or state jurisdiction. In Uttar Pradesh, many taxpayers are under the State Tax department, others under CGST commissionerates. The law and forms are the same. Only the office and officer differ. We handle cases for businesses in Ghaziabad, Noida, Delhi, Gurgaon, Agra and other cities, all online.
Business hours: Monday to Friday 9:00 AM to 6:00 PM, Saturday 10:00 AM to 4:00 PM. Reach us through the contact page.
Your work is handled by experienced professionals who explain every step, check your documents and keep you updated.
Registered company
TaxCaller is run by TaxCaller India LLP (LLPIN AAQ-7388), serving clients since 2018.
Fee told upfront
You know the complete fee, our professional fee and the government fee, before any work starts. No hidden charges.
Support after the work
Notices, renewals, returns and compliance reminders: we stay with your business after the registration is done.
Reviewed By
Reviewed & Verified GST Consultant
Abhinay Rai
Advocate
Abhinay Rai is a Advocate specialising in GST Consultant. The process, documents, timelines and fees on this page are checked against the current rules and government portals, and updated whenever the law, forms or fees change.
A GST consultant handles the GST work that goes beyond routine filing. This includes replying to notices, defending show cause notices, filing appeals, claiming refunds, matching input tax credit with GSTR-2B and advising on rates and invoices. At TaxCaller, our experts also review annual returns and support you during departmental audits under Section 65.
How much does a GST consultant charge?
Fees depend on the work. A simple ASMT-10 reply needs less time than a fraud notice with a hearing or an appeal. At TaxCaller, fees start at ₹799 + GST, and our expert confirms the exact scope on the first call, before work starts. Government payments such as pre-deposits, tax and interest are paid separately at actual.
Do I need a GST consultant if I file my own returns?
Not for every month. Many owners file their own returns without trouble. You need expert help when something unusual happens, such as a notice, a large credit mismatch, a refund claim, an audit or a cancelled registration. A yearly health check also helps, because it finds the gaps that usually trigger scrutiny notices later.
Can a GST consultant reply to a notice on my behalf?
Yes. A consultant can study the notice, reconcile your data and draft the reply. Filing happens through your portal login or as an engaged GST practitioner, and you approve it. For hearings, only persons listed in Section 116 can appear as your authorised representative, such as advocates, practising chartered accountants or enrolled GST practitioners.
What is the time limit to reply to an ASMT-10 notice?
Under Rule 99 of the CGST Rules, you reply in FORM GST ASMT-11 within 30 days of service of the notice, or within any longer time the officer allows. If the officer accepts your explanation, you get ASMT-12. If not, the officer may start audit, inspection or demand proceedings under Section 73, 74 or 74A.
What is Section 74A and does it apply to me?
Section 74A was added by the Finance (No. 2) Act, 2024. It covers demands for tax for Financial Year 2024-25 onwards, both with and without fraud. The notice must issue within 42 months of the annual return due date. For earlier years, Sections 73 and 74 still apply. Check which section your notice quotes.
Is the GST Appellate Tribunal working in 2026?
Yes. The GST Appellate Tribunal was launched on 24 September 2025 and accepts appeals online through its e-filing portal. Backlog appeals were allowed until 31 July 2026 for orders communicated before 1 May 2026. For later orders, you must appeal within three months of receiving the first appeal order, under Section 112 of the CGST Act.
What happens if I ignore a GST notice?
The officer can decide the case without hearing you. A demand order is then issued for tax, interest and penalty. If you still do not pay, recovery under Section 79 can follow, including attachment of your bank account. Ignoring scrutiny or cancellation notices can also lead to suspension or cancellation of your GST registration.
Is a GST consultant the same as a GST practitioner?
Not always. A GST practitioner is a person enrolled under Section 48 and Rule 83 through FORM GST PCT-01, who can file returns and claims for clients on the portal. A GST consultant is a broader term. It may include advocates, chartered accountants and other tax experts who advise and represent you, depending on their qualification.
How long does a GST refund take?
The law asks the officer to decide a complete refund claim within 60 days. If that does not happen, interest of up to 6% a year is payable under Section 56. For zero-rated and, from November 2026, inverted duty refunds, up to 90% can be released provisionally. Delays usually come from incomplete documents or mismatched returns.
Can you help if my GST registration is cancelled?
Yes. If the officer cancelled your registration, you can apply for revocation under Section 30 within 90 days of the cancellation order, after filing pending returns and paying dues. The time can be extended in some cases. If revocation is refused, an appeal under Section 107 is possible. We check which route suits your case.
Do I need to share my GST portal password with you?
Usually no. You can engage an enrolled GST practitioner on the GST portal, which gives them limited access without your password. Returns and replies are still verified with your OTP, EVC or digital signature. For tasks that need your login, we explain why and you stay in control of when it is used.
Can TaxCaller handle GST work outside Ghaziabad?
Yes. GST notices, replies, refunds and appeals are all filed online, so location does not limit the work. Our office is in Ghaziabad, and we serve clients in Delhi NCR and other states through calls, email and WhatsApp. If an in-person hearing is fixed, we discuss the arrangement and any travel cost before the date.