Starting from · ₹799 Tax Consultant Expert Call plan
STARTING FROM₹799
MRP ₹99920% OFF
!ITR, transfer pricing cases due?Last date 30 Nov 2026 · 8 days left
Since 2018Trusted Experience
980+Experts Connected
220+Cities Served
1164+Agents Available
12,650+Founders Trusted
S
Srishti Magoo
★★★★★
Excellent experience with TaxCaller for filing my &
my family members ITR returns. The entire process was
smooth, quick and hassle-free. They are professional,
knowledgeable and guided me through every step with patience.
O
obeid sait
★★★★★
The team has handled my taxes for the past three years,
and it's been a wonderful, hassle-free experience.
Thank you for your consistently quick and efficient service.
P
Pushkar
★★★★★
They are among the best in their field. Their work culture
is highly professional, and their client service is smooth
and reliable. They can confidently be relied on to get the job done.
P
Prasad Sheth
★★★★★
Excellent experience with TaxCaller! The ITR filing
process was smooth, quick, and completely hassle-free.
The CA was knowledgeable, responsive, and explained everything clearly.
A
Apoorv Bansal
★★★★★
Excellent service for ITR filing. The team was highly
professional, responsive, and guided me through the entire
process smoothly. My return was filed accurately and on time.
A
Abhishek Kumar
★★★★★
I was searching for a good CA firm in Ghaziabad and found
TaxCaller. The experience was excellent from start to finish.
The team is responsive, transparent, and genuinely helpful.
U
uma pandey
★★★★★
Great service! TaxCaller India made the entire ITR filing
process quick, smooth, and hassle-free. They answered all
my queries patiently and ensured maximum accuracy.
T
tanu mittal
★★★★★
Excellent job! We've been connected for many years,
and your success truly makes me happy. You are an
incredibly intelligent person. Keep shining, keep growing.
B
Bhanu Pratap Maurya
★★★★★
I am filing my ITR since past 3 years with Abhinav and
Firm is known as TaxCaller and they are professional
interms of ITR rules. They will explain and tell you all
the information.
A
ashish Sharma
★★★★★
I am providing my honest reviews:
No.1 service ...
A
AARYAN GROUP
★★★★★
Honestly, finding a good CA firm in Ghaziabad was
confusing, but TaxCaller India made it simple.
I contacted them for GST work and the experience was smooth.
N
News Speaks
★★★★★
If you're looking for a reliable CA firm in Ghaziabad,
TaxCaller India is a great choice. They provide complete
taxation and compliance solutions including GST.
A
Anshul Chaprana
★★★★★
Got my GST registration done through TaxCaller CA firm.
Process was quite smooth, they guided properly on documents
and didn't waste time. Overall good experience.
How we work
Online · Call · WhatsApp
Quick answer
A tax consultant helps you plan income tax, pick the right regime, handle capital gains and NRI tax, and reply to notices on time. At TaxCaller, an expert call costs ₹799 + GST, a notice reply ₹2,099 + GST and a yearly tax plan ₹2,999 + GST. Tax, interest and government fees are paid separately.
Government fees and taxes are extra where applicable. Our expert confirms the final amount on the first call. No hidden charges.
About Tax Consultant Services
A tax consultant is a person who studies your income, investments and tax papers, and then tells you what to do. Most people need one at a few key moments. You may be choosing between the old and new tax regime. You may have sold shares, a flat or gold. You may be an NRI with income in India. Or you may have just received a notice from the Income Tax Department and do not know what it means.
TaxCaller gives you direct access to a tax expert over call and WhatsApp. We read your papers, explain the law in plain words and give you a written answer or a filed reply. We have been helping taxpayers since 2018 from our head office in New Delhi, and we work online with clients across India.
This page explains what a tax consultant does, when you need one, how notices and appeals work under the Income-tax Act, 1961 and the new Income-tax Act, 2025, who can legally represent you, and what our help costs. If you only need your yearly return filed, see our income tax return filing page instead.
Complete guide
Choose a topic to open it. Every answer gives the rule or section it comes from.
01 Topic 1 of 22
What Does a Tax Consultant Do?
A tax consultant gives advice on tax. The word covers many kinds of help, from a short call to a full reply before the Assessing Officer. In India, most people use the term for an income tax adviser who works with individuals, families and small businesses.
Here is what a good income tax adviser does for you:
Reads your full picture. Salary, rent, business income, capital gains, interest and foreign income are looked at together, not in parts.
Plans your tax. They compare the old and new regimes, check which deductions you can really use and tell you the tax you will owe.
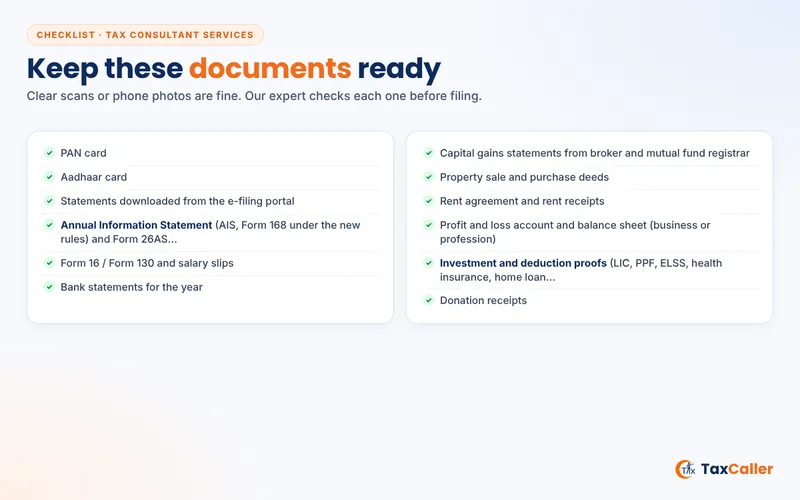
Checks your data. They match your figures with the Annual Information Statement and the tax credit statement before anything is filed.
Handles notices. They read the notice, find the reason, collect proof and draft a reply that answers the exact point raised.
Fixes errors. They file rectification requests, revised returns or updated returns when a mistake has crept in.
Guides appeals. If an order goes against you, they explain your appeal options and the time limit.
Keeps you on schedule. They remind you about advance tax instalments and filing dates.
A tax consultant is different from a return preparer. A preparer files what you give. A consultant asks questions, spots risks and tells you the tax effect of a choice before you make it. That advice is what saves money and stress later.
Not everyone needs paid help every year. A person with only one salary, no big investments and a clean Form 16 can often file on their own. You should talk to an expert in these cases:
Salaried people with choices to make: new job mid-year, two employers, arrears, ESOPs, house rent, home loan or a big bonus.
Investors and traders: sale of shares, mutual funds, property, gold or crypto assets, or intraday and F&O trading.
Freelancers and professionals: doctors, lawyers, designers, consultants and creators who want to use presumptive taxation or claim expenses correctly.
Small business owners: proprietors and partners who must pay advance tax and keep books.
NRIs and returning Indians: anyone with rent, interest or capital gains in India, or a change in residential status.
Senior citizens: pensioners with interest income who want to avoid excess TDS and claim refunds.
Anyone with a notice: an intimation, a demand, a scrutiny notice or a reassessment show cause notice.
Families with big life events: inheritance, gifts, marriage, a property purchase or moving abroad.
When does it become urgent? When a notice has a reply date. When the advance tax date is near and you have a big gain. When you are about to sell an asset and want to plan the tax first. In these cases a delay can cost interest, a late fee or even a penalty.
Working as a consultant yourself? Your tax is different
Many people search for this topic because they are paid as a consultant, not as an employee. The tax rules then change in four ways:
Point
Salaried employee
Independent consultant
How income is taxed
Under the head salaries
As profits of a business or profession
Standard deduction
₹75,000 in the new regime, ₹50,000 in the old regime
Not available; real expenses are claimed instead
Tax deducted by payer
TDS on salary by the employer
TDS on professional fees by the client, often at 10%
Usual return form
ITR-1 or ITR-2
ITR-3, or ITR-4 under presumptive tax
A resident professional can declare 50% of gross receipts as income under section 44ADA of the 1961 Act, now carried into section 58 of the 2025 Act. The limit is ₹50 lakh of receipts, raised to ₹75 lakh when cash receipts are not more than 5% of the total. Our expert checks whether this beats keeping full books in your case.
Zubair Income Tax Expert
Have a question on this topic? Ask Zubair on a free call.
Our work covers direct tax for individuals, HUFs, freelancers and small businesses. GST and TDS work is handled on their own pages, which are linked below.
Service
What you get
Who it suits
Expert call
A one-to-one call on your question, with the answer in writing
Anyone with a specific tax doubt
Tax planning
Income and investment review, regime comparison and a written tax-saving plan
Salaried people, professionals, investors
Notice reply
Reading of the notice, drafting and filing of the reply on the portal, and follow-up on the same notice
Anyone who has received a notice
Capital gains advice
Gain calculation, exemption check and advance tax planning
Sellers of shares, funds, property or gold
NRI tax advice
Residential status check, treaty relief and refund planning
NRIs, OCI holders, returning Indians
Rectification and appeal guidance
Review of the order, rectification request or appeal plan
Anyone with a wrong demand or order
Freelancer and consultant income
Choice between presumptive income and regular books, expense review and ITR form check
Doctors, designers, IT consultants, creators
Advance tax planning
Estimate of tax for the year and instalment schedule
Business owners, freelancers, investors
Need your return filed after the advice? Our ITR filing service does that. For TDS on salary, rent or property payments, see TDS return filing. For indirect tax questions, our GST consultant page is the right place.
What we do not take on
Some tax work needs a specific licence or a large team. Statutory audit, tax audit under section 44AB of the 1961 Act and certificates such as Form 15CB must be signed by a chartered accountant in practice. Transfer pricing studies for multinational groups are also outside our scope. If your case needs any of these, we tell you on the first call and point you to the right professional.
The new regime under section 115BAC of the 1961 Act is the default. You pay lower slab rates but give up most deductions. The old regime keeps deductions such as section 80C, 80D and home loan interest, but its slab rates are higher.
New regime slab rates for FY 2025-26 (AY 2026-27), as published on the e-filing portal:
Total income
Tax rate
Up to ₹4,00,000
Nil
₹4,00,001 to ₹8,00,000
5%
₹8,00,001 to ₹12,00,000
10%
₹12,00,001 to ₹16,00,000
15%
₹16,00,001 to ₹20,00,000
20%
₹20,00,001 to ₹24,00,000
25%
Above ₹24,00,000
30%
A resident individual in the new regime gets a rebate under section 87A of up to ₹60,000 if total income does not exceed ₹12 lakh. In the old regime the rebate is up to ₹12,500 for income up to ₹5 lakh. The same slab rates apply for tax year 2026-27 under section 202 of the 2025 Act.
Can you switch every year?
If you have no business or professional income, you can pick the regime each year in the return itself, filed by the due date.
If you have business or professional income, you must opt out in the prescribed form by the due date to leave the new regime (Form 10-IEA for years under the 1961 Act). Coming back to the new regime is allowed only once in your lifetime.
Our expert works out your tax both ways using your real numbers. Special rates on capital gains, the rebate limit and the standard deduction all change the answer. A simple rule of thumb is not enough.
Abhinay Rai Income Tax Expert
Have a question on this topic? Ask Abhinay on a free call.
Who Pays 42% Tax in India? Surcharge and Cess Explained
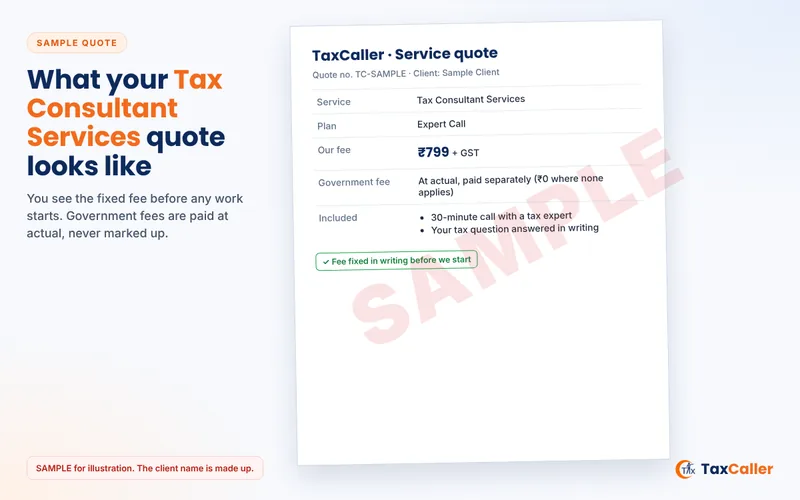
Tax Consultant Services: SAMPLE quote, for illustration only
The 42% figure applies only to people with total income above ₹5 crore who stay in the old regime. It comes from three parts added together: the 30% slab rate, a 37% surcharge on that tax and a 4% health and education cess. Worked out, 30% x 1.37 x 1.04 gives an effective top rate of about 42.74%.
The surcharge rates for tax year 2026-27 are set by the Finance Act, 2026 (section 3 of that Act for the 2025 Act years):
Total income
Surcharge, old regime
Surcharge, new regime (section 202)
Up to ₹50 lakh
Nil
Nil
Above ₹50 lakh to ₹1 crore
10%
10%
Above ₹1 crore to ₹2 crore
15%
15%
Above ₹2 crore to ₹5 crore
25%
25%
Above ₹5 crore
37%
25% (capped)
Three points change the real answer:
New regime cap. Surcharge stops at 25%, so the top effective rate is 39% (30% x 1.25 x 1.04).
Capital gains and dividends. Surcharge on the part of tax that comes from dividends and capital gains cannot exceed 15%.
Marginal relief. If income crosses a threshold by a small amount, the extra tax cannot be more than the extra income.
The same rates applied for AY 2026-27 under the 1961 Act, as the rate chart on the Income Tax Department site shows. For high earners, choosing the regime and timing large gains is where advice saves the most.
NRI Tax Advice: Residential Status, Treaties and Refunds
For an NRI, the first question is not the tax rate. It is residential status. Your status decides which income India can tax.
Under section 6 of the 1961 Act, carried into section 6 of the 2025 Act, an individual is resident in a year if:
they are in India for 182 days or more in the year, or
they are in India for 60 days or more in the year and 365 days or more in the 4 years before it.
Some special rules apply:
An Indian citizen who leaves India for a job abroad is resident only on the 182-day test.
An Indian citizen or person of Indian origin visiting India, whose Indian income is above ₹15 lakh, faces a 120-day test in place of 60 days.
A citizen with Indian income above ₹15 lakh who is not liable to tax in any other country can be treated as a deemed resident.
A person can be resident but not ordinarily resident, for example after 9 of the last 10 years as a non-resident.
Our expert helps NRIs with:
Tax on rent, NRO interest, dividends and capital gains in India.
Relief under the Double Taxation Avoidance Agreement with your country, backed by a Tax Residency Certificate.
Refunds where TDS was cut at a higher rate than the real tax.
A lower TDS certificate before selling property, under section 197 of the 1961 Act or its 2025 Act equivalent.
Planning for the year you return to India.
Interest on an NRE account is exempt for those who qualify as non-residents under FEMA rules. Our expert confirms this for your case.
Residents with foreign income or assets
The reverse case needs care too. A resident who holds foreign shares, ESOPs or RSUs of a foreign employer, or a bank account abroad, must report them in Schedule FA of the return. Foreign tax already paid is claimed as a credit by filing Form 67 within the time the rules allow, for years under the 1961 Act. Missing a foreign asset can attract action under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015. Banks abroad now share account data with India under automatic exchange of information, and the CBDT uses it to find foreign assets missing from returns.
Shadab Income Tax Expert
Have a question on this topic? Ask Shadab on a free call.
Income Tax Notices: What Each One Means and How to Reply
A notice is not always bad news. Many are simple requests to explain a mismatch. But every notice has a reply date, and silence can lead to added income, a demand or penalty. The table shows common notices and their section under both Acts.
Notice
1961 Act
2025 Act
What it means
Defective return
Section 139(9)
Section 263(7)
Your return has a defect. Fix it within 15 days or it may be treated as not filed.
Intimation after processing
Section 143(1)
Section 270(1)
The CPC has processed your return and may show a demand, refund or adjustment.
Proposed adjustment
Section 143(1)(a)
Section 270(2)
The department plans to change a figure. You get 30 days to respond.
Scrutiny notice
Section 143(2)
Section 270(8)
Your return is selected for detailed checking. You must give evidence.
Show cause before reopening
Section 148A
Section 281
The officer has information that income escaped tax and asks why the case should not be reopened.
Reassessment notice
Section 148
Section 280
The case is reopened. You must file a return for that year within the time given.
Rectification
Section 154
Section 287
A mistake apparent from the record is being corrected, by you or the department.
Time limits the department must follow
An intimation cannot be sent after 9 months from the end of the financial year in which the return was filed (section 270(4) of the 2025 Act; same limit in section 143(1)).
A scrutiny notice cannot be served after 3 months from the end of the financial year in which the return was filed (section 270(9); same limit in section 143(2)).
Under section 282 of the 2025 Act, a reopening notice under section 280 generally cannot be issued after 4 years and 3 months from the end of the tax year. It can go up to 6 years and 3 months only where escaped income is ₹50 lakh or more.
For tax years that began before 1 April 2026, the old Act's reassessment rules, including the time limits in section 149, still apply.
How our expert replies
We check the notice is genuine using its Document Identification Number (DIN). CBDT Circular No. 19/2019 requires a DIN on department communications.
We read the exact issue and the data behind it, such as the Annual Information Statement.
We collect only the proof that answers that issue.
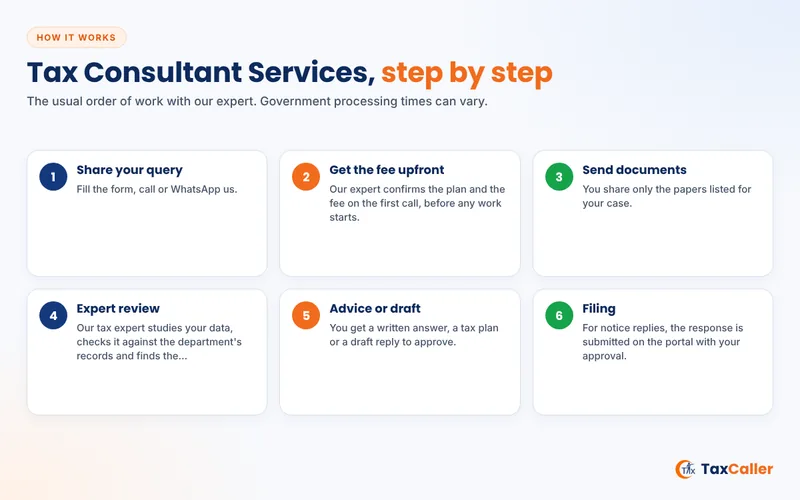
We draft a short, point-wise reply and submit it under e-Proceedings on the portal, or help you submit it.
We track the outcome and handle follow-up questions on the same notice.
A response under e-Proceedings cannot be edited or withdrawn after submission. That is why the draft must be right the first time.
Rectification, Appeals and Revision After an Order
If an order or intimation is wrong, you have three main routes. The right one depends on the type of error.
1. Rectification
Use this for a mistake apparent from the record, such as a TDS credit not given or a wrong arithmetic figure. Under section 287 of the 2025 Act, which matches section 154 of the 1961 Act, an amendment cannot be made after 4 years from the end of the financial year in which the order was passed. The authority must decide your application within 6 months from the end of the month in which it is received.
2. Appeal to the Commissioner (Appeals)
Use this when you disagree on facts or law. For years governed by the 1961 Act, the appeal is filed online in Form 35 within 30 days of receiving the order or demand. The Commissioner (Appeals) may admit a late appeal if there is sufficient cause. The government appeal fee is:
Assessed income
Appeal fee
₹1,00,000 or less
₹250
₹1,00,001 to ₹2,00,000
₹500
Above ₹2,00,000
₹1,000
Any other matter
₹250
Under the 2025 Act, first appeals sit in sections 356 to 360. The portal FAQs confirm that appeals for AY 2026-27 or earlier, even if filed after 1 April 2026, are still governed by the 1961 Act under section 536(2)(c) of the 2025 Act.
3. Further appeal and revision
The appeal ladder is unchanged: Assessing Officer, then Joint Commissioner (Appeals) or Commissioner (Appeals), then the Income Tax Appellate Tribunal, then the High Court and the Supreme Court. You can also ask the Principal Commissioner to revise an order in your favour under section 264 of the 1961 Act. The 2025 Act keeps a similar power in section 378.
Our expert tells you which route fits, what it will cost and how long it may take. If your case needs a lawyer to appear at the Tribunal or a court, we tell you that clearly at the start.
Who Can Represent You Before the Income Tax Department?
You can appear in person, or send an authorised representative. The law decides who can be that person. The rule is in section 288 of the 1961 Act. For proceedings under the new law, it is section 515 of the 2025 Act. Both lists are almost the same.
An authorised representative must have your written authority and must be one of these:
a relative, or a person regularly employed by you;
an officer of a scheduled bank where you have a current account or regular dealings;
a legal practitioner entitled to practise in any civil court in India, such as an advocate;
an accountant, meaning a chartered accountant with a valid certificate of practice;
a person who has passed an accountancy examination recognised by the CBDT;
a person with the educational qualifications prescribed in the Income-tax Rules.
Who cannot represent you? A person dismissed from government service, a person convicted of an offence linked to income tax proceedings or of fraud, or an insolvent person can be barred, for the periods the law sets. A representative found guilty of misconduct can also be barred by the authority the law names.
One exception: if you are summoned to give a statement on oath, you must attend in person. A representative cannot give that statement for you.
Online notices: the e-Proceedings service lets you add an authorised representative to respond to a notice on your behalf. Only one authorised representative can be active for a proceeding at a time, and you can withdraw the authority later.
Before you hand over your login or sign an authority letter, check that the person falls in one of the categories above. Ask for their enrolment or membership number and verify it with the Bar Council or the professional body.
Shreya Income Tax Expert
Have a question on this topic? Ask Shreya on a free call.
Can You Become a Tax Consultant Without Being a CA?
Yes. No single licence is needed to give tax advice or prepare returns in India. A CA qualification is needed only for work the law reserves for chartered accountants, such as audits and certain certificates.
Appearing for a client before the Income Tax Department is different. The person must fit a category in section 515 of the 2025 Act. Two of those categories rest on a qualification other than CA:
Rule 251 of the Income-tax Rules, 2026: passing a recognised accountancy examination, such as the final examination of the ICSI or ICMAI.
Rule 252: a degree in Commerce or Law from a university in India, or an equivalent foreign degree recognised by the Association of Indian Universities.
Rules 250 to 268 also set out how such income-tax practitioners are registered and how a complaint of misconduct against them is inquired into. An advocate enrolled with a State Bar Council can represent clients as a legal practitioner.
Skills and career path
Most tax consultants start with a B.Com, BBA or law degree. Many then add CA, CMA, CS or a diploma in taxation. Daily work needs a sound grasp of the Act, careful reading of AIS data, clear writing for notice replies and comfort with the e-filing portal. Typical employers are tax firms, companies, banks and fintech platforms. Many experienced people later start an independent practice.
Tax consultant salary
Pay depends on city, firm size and experience. Salary surveys quoted by education sites report an average of about ₹6.7 lakh to ₹7.4 lakh a year in India. Freshers earn less, and senior advisers in large firms earn much more. Treat these as reported market figures, not official data.
Anyone can call themselves a tax adviser. So it pays to check before you share your PAN, bank statements and login. Use this checklist.
Questions to ask before hiring
Who exactly will handle my case, and what is their qualification?
Can that person represent me if the case goes to a hearing? Under which category of section 288 or section 515?
What is included in the fee, and what is extra? Are government fees and GST separate?
Will I get the advice or the draft reply in writing before it is filed?
How will my documents be stored, and who can see them?
How fast do you respond when a notice has a short deadline?
Red flags
A promise of a refund before seeing your papers.
Advice to claim deductions you have no proof for.
Refusal to give a written fee or a receipt.
A request to share your OTP or e-filing password over chat.
Consultant, accountant or software?
Option
Good for
Limits
Tax software or self-filing
Simple salary returns with clean data
Cannot judge choices, notices or grey areas
Accountant or bookkeeper
Keeping books, ledgers and reconciliations
Tax advice and representation may be outside their role
Tax consultant or tax expert
Planning, regime choice, gains, NRI tax and notices
Representation depends on the person's legal category
GST practitioner
GST registration, returns, refunds and e-way bill data for a business that authorises them, under section 48 of the CGST Act and rule 83 of the CGST Rules
Enrolment through Form GST PCT-01 covers GST work only, not income tax
Advocate
Notices, appeals and court cases, as a legal practitioner under section 288 or section 515
Bookkeeping and routine return filing are usually not their focus
CA firm
Tax audit, certification and statutory audit
Usually higher fees for small personal matters
For GST disputes, section 116(2) of the CGST Act lets these people appear for you before GST officers and the Appellate Authority: a relative or regular employee, an advocate, a practising CA, cost accountant or company secretary, a qualified retired tax officer, and an enrolled GST practitioner. When a GST practitioner prepares your return, you still confirm that its facts are true before it is filed.
Tax Consultant Fees and Government Charges, Clarified
We keep our fee and the government's charges apart, so you know exactly what you pay to whom.
Plan
What is included
TaxCaller fee
Expert Call
One income tax consultation of 30 minutes, with the answer in writing
₹799 + GST (MRP ₹999)
Income Tax Notice Reply
Reading and explaining one notice, drafting and filing the reply on the portal, and follow-up on the same notice
₹2,099 + GST (MRP ₹2,999)
Tax Planning
Review of income and investments, old vs new regime comparison and a written tax-saving plan for the year
₹2,999 + GST (MRP ₹4,999)
TaxCaller's fee is the amount above + GST. It does not include any government charges. These are paid separately, at actual, directly to the department:
Tax, interest and late fee: any tax demand, interest under the Act or late filing fee is paid by challan in your name.
Appeal fee: ₹250, ₹500 or ₹1,000 for a first appeal under the 1961 Act, based on assessed income.
Updated return: the extra tax payable with an updated return goes to the government, not to us.
A short consultation has no government fee at all. Work outside these plans, such as an appeal draft, a complex capital gains case or a multi-year reassessment, is quoted on the first call before we begin. There are no hidden charges.
What decides a tax consultant's fee
Fees across the market vary a lot, so compare the scope and not just the number. These points move the fee up or down:
The number of income heads, such as salary, rent, gains and business.
The count of trades or property deals to work through.
Foreign income, foreign assets or a treaty claim.
Whether a notice is a simple mismatch or a full scrutiny or reopening.
How many years and how many hearings the case needs.
How quickly the work must be done before a deadline.
Ask for the scope in writing before you pay anyone.
Ongoing Compliance: Advance Tax and Your Yearly Tax Calendar
Tax is not a one-time job in July. Under section 404 of the 2025 Act, anyone whose tax for the year, after TDS, is ₹10,000 or more must pay advance tax during the same year. A resident senior citizen aged 60 or above with no business or professional income does not need to pay advance tax.
Due date
Advance tax to be paid by then
15 June
15% of the tax for the year
15 September
45% of the tax for the year
15 December
75% of the tax for the year
15 March
The full tax for the year
Taxpayers under the presumptive scheme in section 58 of the 2025 Act (sections 44AD and 44ADA of the 1961 Act) must pay the whole amount in one instalment by 15 March. The next instalment for tax year 2026-27 falls on 15 December 2026.
Return due dates under section 263 of the 2025 Act
31 July: all other taxpayers, such as salaried people, pensioners and investors without business income.
31 August: people with business or professional income whose accounts do not need audit, and partners of such firms.
31 October: companies and taxpayers whose accounts need audit.
30 November: taxpayers who must file a transfer pricing report.
A belated return can be filed within 9 months from the end of the tax year. A revised return can be filed within 12 months. An updated return can be filed within 48 months from the end of the financial year after the tax year, with extra tax.
Dates for AY 2026-27 returns still open in November 2026
Returns for FY 2025-26 are filed under the 1961 Act. The CBDT moved two dates for this year: the tax audit report to 21 October 2026 and the return for audit cases to 21 November 2026, by CBDT Circular No. 7/2026 dated 28 September 2026. Transfer pricing cases still have 30 November 2026. A belated return for AY 2026-27 can be filed by 31 December 2026 under section 139(4), with the late fee under section 234F where it applies. A revised return under section 139(5) can be filed up to 31 March 2027, with a fee under section 234-I if filed after 31 December 2026.
With a yearly plan, our expert reminds you before each date and updates your estimate when a large income comes in. For business clients, regular bookkeeping makes these estimates easier.
In 2026 India replaced its six-decade-old income tax law. Here is what matters for your tax advice.
1. The Income-tax Act, 2025 is now in force
The new Act replaced the Income-tax Act, 1961 from 1 April 2026, as announced in the CBDT press release of that date. Parliament passed it on 12 August 2025 and it received assent on 21 August 2025. The government has said the aim is to simplify the law without changing tax policy.
2. Tax year replaces previous year and assessment year
The 2025 Act applies to tax years that begin on or after 1 April 2026. FY 2025-26 and earlier years stay under the 1961 Act. This is set out in the savings clause, section 536 of the 2025 Act. So a notice for AY 2024-25 still cites section 143 or 148, while a notice for tax year 2026-27 will cite section 270 or 280.
3. New rules and new form numbers
The CBDT notified the Income-tax Rules, 2026 on 20 March 2026, with new forms. Form 16 is replaced by Form 130 under rule 215 of the new rules, and Form 168 is the Annual Information Statement under rule 245. Our expert checks which form number applies to your year.
4. Longer window for revised returns
Section 263(5) of the 2025 Act allows a revised return within 12 months from the end of the tax year, in place of the earlier 9 months. A revised return filed after 9 months attracts a fee under section 428(b): ₹1,000 if total income is up to ₹5 lakh and ₹5,000 in other cases.
5. Later due date for non-audit business returns
Section 263(1) now gives 31 August as the due date for people with business or professional income who do not need an audit. Salaried people and others still have 31 July.
6. Updated return after a reopening notice
Under section 263(6), an updated return can also be filed in response to a notice under section 280, within the time stated in the notice.
7. Appeals and reassessment during the change
The e-filing portal FAQs confirm that pending appeals continue under the 1961 Act. Reassessment for tax years before 1 April 2026 also follows the old Act's rules. Our expert reads each notice with the right Act for that year.
Real experts, not a call centre. Your query goes to a tax expert who reads your papers.
Registered firm. TaxCaller India LLP, LLPIN AAQ-7388, serving clients since 2018.
Content reviewed by an advocate. Our tax pages are reviewed by Abhinay Rai, Advocate.
Fee told upfront. You know our fee + GST, and the government charges, before work starts.
Written answers. Advice and draft replies come in writing, so you have a record.
Support after the work. Follow-up questions on the same notice are covered.
Grievance redressal. A named grievance officer answers complaints within 48 hours.
Local help, online across India
Our head office is in New Delhi, and many clients come from Noida, Ghaziabad, Gurgaon and Agra. Income tax is a central law, so the same rules apply in every state. Most notices are now issued and answered online. That means we can help you wherever you live, and even from abroad if you are an NRI.
Searching for a tax consultant near me in Ghaziabad? Our tax consultant in Ghaziabad page lists local details. Clients from Raj Nagar, Indirapuram, Vaishali, Kaushambi and Vasundhara can meet us by appointment. Everyone else gets the same service over call, WhatsApp and email.
Your work is handled by experienced professionals who explain every step, check your documents and keep you updated.
Registered company
TaxCaller is run by TaxCaller India LLP (LLPIN AAQ-7388), serving clients since 2018.
Fee told upfront
You know the complete fee, our professional fee and the government fee, before any work starts. No hidden charges.
Support after the work
Notices, renewals, returns and compliance reminders: we stay with your business after the registration is done.
Reviewed By
Reviewed & Verified Tax Consultant
Abhinay Rai
Advocate
Abhinay Rai is a Advocate specialising in Tax Consultant. The process, documents, timelines and fees on this page are checked against the current rules and government portals, and updated whenever the law, forms or fees change.
A tax consultant studies your income, investments and tax records, then advises on how much tax you owe and how to lower it legally. They compare tax regimes, plan capital gains and advance tax, check your data against the AIS, and draft replies to income tax notices. Some can also represent you before tax authorities.
How much does a tax consultant charge in India?
Fees vary with the work. At TaxCaller, a 30-minute expert call costs ₹799 + GST, a reply to one income tax notice costs ₹2,099 + GST, and a yearly tax plan costs ₹2,999 + GST. Any tax, interest, late fee or appeal fee is paid separately to the government at actual.
Is a tax consultant the same as a chartered accountant?
Not always. A chartered accountant holds a certificate of practice from ICAI and can do audits. A tax consultant is any adviser on tax, and may be an advocate, a CA, or someone with other qualifications. For representation before the department, the person must fall in a category listed in section 288 or 515.
Can I become a tax consultant without being a CA?
Yes. Tax advice and return preparation need no special licence. To represent clients before the Income Tax Department, you must fit section 515 of the 2025 Act, for example with a commerce or law degree under rule 252, or an ICSI or ICMAI final pass under rule 251. Audits and some certificates still need a practising CA.
Who can represent me before the Income Tax Department?
Under section 288 of the 1961 Act and section 515 of the 2025 Act, you can authorise a relative, your regular employee, a bank officer, an advocate, a practising chartered accountant, or a person with a recognised accountancy exam or prescribed qualification. The authority must be in writing and signed by you.
Which tax regime is better for me?
It depends on your numbers. The new regime has lower slabs and a rebate up to ₹60,000 for income up to ₹12 lakh, but few deductions. The old regime suits people with large deductions such as home loan interest, 80C and 80D. Our expert calculates your tax both ways before you decide.
What should I do if I receive an income tax notice?
Do not ignore it and do not panic. Check the section, the year and the reply date. Verify the DIN on the e-filing portal. Then compare the issue with your AIS and return. Reply with only the proof that answers the point raised, before the due date, through e-Proceedings on the portal.
How can I check whether an income tax notice is genuine?
Every genuine notice from the department must carry a Document Identification Number, as required by CBDT Circular No. 19/2019. You can check the DIN using the notice authentication service on the e-filing portal. Also log in and look under pending actions. Never click links or share OTPs from unknown messages.
Can I file a revised return instead of replying to a notice?
Sometimes. If you find your own error before assessment, a revised return can fix it within the legal window. For a Seek for Clarification notice, the portal accepts no reply once a revised return is filed. For scrutiny or reopening notices, you must still reply. Our expert advises which path is safer.
Do NRIs need a tax consultant in India?
Many do. NRIs with rent, interest or capital gains in India often face TDS at high rates, and the residential status rules are detailed. A tax expert checks your status under section 6, claims treaty relief with a Tax Residency Certificate, and helps you get refunds of excess TDS through your Indian return.
Who has to pay advance tax?
Anyone whose tax for the year, after TDS, is ₹10,000 or more must pay advance tax in four instalments by 15 June, 15 September, 15 December and 15 March. Resident senior citizens without business income are exempt. People with only salary income usually do not pay it because the employer deducts TDS.
What is the time limit to appeal against an assessment order?
For years under the 1961 Act, a first appeal to the Commissioner (Appeals) is filed in Form 35 within 30 days of receiving the order or demand notice. The government fee is ₹250 to ₹1,000, based on assessed income. A late appeal may be admitted only if you show sufficient cause for the delay.
Does the Income-tax Act, 2025 affect my old notices?
Not for older years. The 2025 Act applies to tax years starting on or after 1 April 2026. Notices, appeals and penalties for FY 2025-26 and earlier years continue under the 1961 Act, as section 536 of the new Act provides. New section numbers apply from tax year 2026-27 onwards.
How often should I consult a tax expert?
Most people need advice once a year, ideally before March, to plan investments and pick a regime. You should also talk to an expert before selling a large asset, when you change jobs or residence, before an advance tax date with large income, and as soon as any notice or demand arrives.
Is my financial data safe when I share it online?
Share data only with an adviser who tells you who will see it and how it is stored. At TaxCaller, your papers are used only for your case. Never share your e-filing password or OTP over chat. If needed, add an authorised representative through e-Proceedings, which you can withdraw at any time.