Srishti Magoo
Excellent experience with TaxCaller for filing my & my family members ITR returns. The entire process was smooth, quick and hassle-free. They are professional, knowledgeable and guided me through every step with patience.
Get your income tax return filing done online by tax experts, with the right ITR form, the better tax regime and help until your refund arrives.
Content updated 15 Nov 2026 · Verified by expert 24 Oct 2026
File your Income Tax Return
50+ onlinePay 38% to start the work. Pay the balance only after the government proof (the ITR-V acknowledgement) is issued.
How we work
Online · Call · WhatsApp
Quick answer
Income tax return filing means reporting your yearly income, deductions and taxes paid to the Income Tax Department on its e-filing portal. For FY 2025-26 (AY 2026-27), you file under the Income-tax Act, 1961. Salaried people had to file by 31 July 2026. Missed it? A belated return is allowed until 31 December 2026, with a late fee.
Starting fee of each option. Open any card to see every plan, documents and steps.
Most Popular
ITR-1 Filing
ITR 1 filing for salaried people and pensioners, with Form 16 and AIS matching, a regime check and e-verification…
₹799 + GST
No govt. filing fee
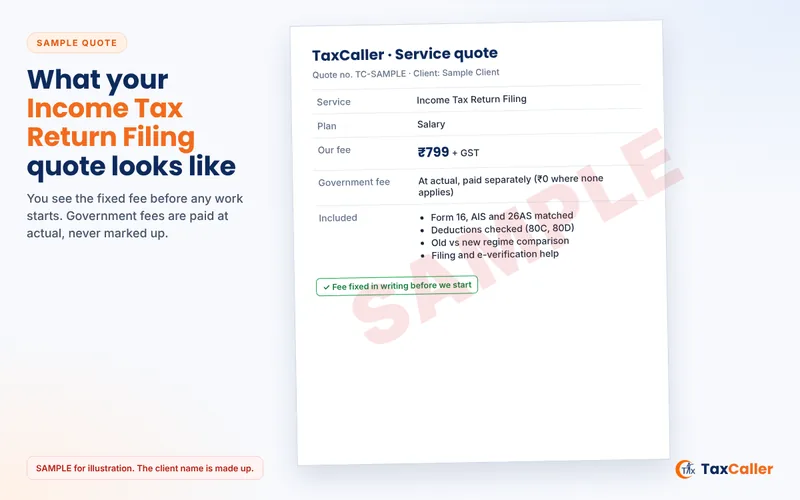
Fee confirmed in writing before you pay
See all plans & details →What you'll get
ITR-2 Filing
Get your ITR 2 filing done by tax experts who work out your capital gains, foreign assets and regime choice, then file…
₹1,874 + GST
No govt. fee
Fee confirmed in writing before you pay
See all plans & details →What you'll get
ITR-4 Filing
Get your ITR 4 filing done online by tax experts, for shop owners, freelancers, professionals and transporters using…
₹1,999 + GST
No govt. fee
Fee confirmed in writing before you pay
See all plans & details →What you'll get
ITR-3 Filing
Get your ITR 3 filing done online by tax experts, with your P&L, balance sheet, F&O working and regime choice handled…
₹2,999 + GST
No govt. fee
Fee confirmed in writing before you pay
See all plans & details →What you'll get
Government fees and taxes are extra where applicable. Our expert confirms the final amount on the first call. No hidden charges.
All 12 options
Each has its own page with plans, documents, steps and the law it follows. The fee shown is our starting fee; government fees are paid at actual.
From ₹799 + GST
No govt. filing fee
From ₹1,874 + GST
No govt. fee
From ₹2,999 + GST
No govt. fee
From ₹1,999 + GST
No govt. fee
From ₹2,999 + GST
No govt. fee
From ₹3,999 + GST
No govt. fee
From ₹4,999 + GST
No govt. fee
From ₹1,799 + GST
No govt. fee; tax extra
From ₹2,099 + GST
No govt. fee
From ₹999 + GST
Nil (late fee and interest at actual)
From ₹499 + GST
+ Govt. fees at actual
From ₹799 + GST
Income tax return filing is the yearly step where you tell the government how much you earned, what tax was already cut, and what you still owe or should get back. You file it online on the official Income Tax e-filing portal. The return is called an ITR, and there are seven forms, from ITR-1 to ITR-7.
This year is a little unusual. A new law, the Income-tax Act, 2025, came into force on 1 April 2026. But your return for income earned from April 2025 to March 2026 is still filed under the old Income-tax Act, 1961, for Assessment Year 2026-27. The first return under the new law is for Tax Year 2026-27, and it is due only in 2027.
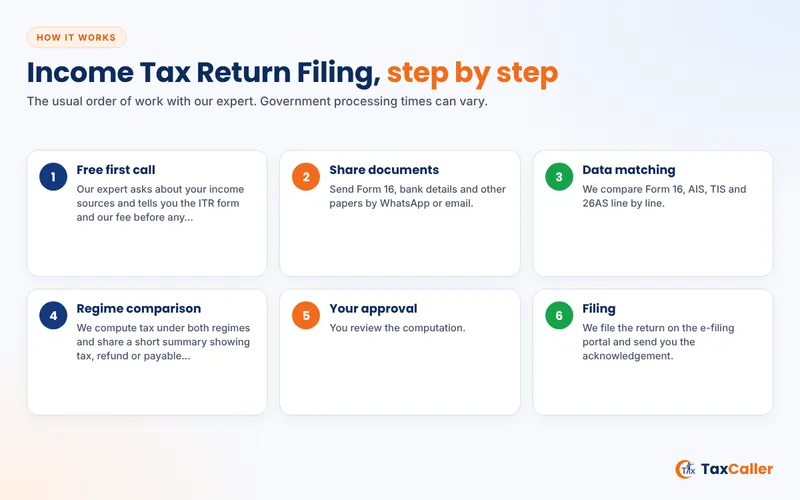
At TaxCaller, our tax experts collect your documents, match them with your AIS and Form 26AS, compare the old and new regimes, file the return and help you e-verify it. We then stay with you for refunds, revisions and notices. You talk to one person from start to finish.
Complete guide
Choose a topic to open it. Every answer gives the rule or section it comes from.
01 Topic 1 of 20
An income tax return is a form that reports your income for one financial year. It shows your income from each source, the deductions you claim, and the taxes already paid through TDS, TCS, advance tax or self-assessment tax. The result is one of three things: tax payable, refund due, or nil.
A simple example: Riya earns a salary of ₹9 lakh in FY 2025-26 and ₹50,000 as FD interest. Her bank cut ₹5,000 as TDS on the interest. Under the new regime, her taxable income after the ₹75,000 standard deduction is below ₹12 lakh, so the section 87A rebate makes her tax nil. Her ITR shows ₹5,000 paid against nil tax, so she gets ₹5,000 back. Without a return, that money stays with the government.
Three terms you will see often:
So in 2026 you file for AY 2026-27 under the old Act. In 2027 you will file for Tax Year 2026-27 under the new Act. These are two separate returns for two separate years, not two returns for the same income.
The five heads of income. Every rupee you report sits under one of five heads in the 1961 Act. The heads you have decide your ITR form and the schedules you fill.
| Head of income | Typical examples | Sections (1961 Act) |
|---|---|---|
| Salaries | Salary, pension, bonus, perquisites | Sections 15 to 17 |
| House property | Rent from a let-out flat or shop, home loan interest | Sections 22 to 27 |
| Business or profession | Shop, trading, freelancing, F&O, consulting fees | Sections 28 to 44DB |
| Capital gains | Sale of shares, mutual fund units, property or gold | Sections 45 to 55A |
| Other sources | Savings and FD interest, dividends, gifts above ₹50,000 from non-relatives, family pension | Sections 56 to 59 |
02 Topic 2 of 20
Under section 139(1) of the Income-tax Act, 1961, an individual must file if total income before Chapter VI-A deductions (80C, 80D and so on) is more than the basic exemption limit. For FY 2025-26, those limits are:
| Taxpayer | New regime limit | Old regime limit |
|---|---|---|
| Below 60 years | ₹4,00,000 | ₹2,50,000 |
| Senior citizen, 60 to 79 years | ₹4,00,000 | ₹3,00,000 |
| Super senior citizen, 80 years or more | ₹4,00,000 | ₹5,00,000 |
Important: the rebate under section 87A does not remove the duty to file. Someone with ₹10 lakh taxable income under the new regime may pay zero tax, but income is above ₹4 lakh, so the return is still required.
You must also file, even below the limit, if in the year you:
The first three come from the seventh proviso to section 139(1). The next three come from Rule 12AB (CBDT Notification No. 37/2022). The foreign asset rule is in the fourth proviso to section 139(1).
Always required: companies, firms and LLPs must file every year, even with a loss or zero income. NRIs must file if Indian income is above the basic exemption limit or if they want a refund of TDS cut in India. Residents aged 75 or more with only pension and interest from the same specified bank can skip the return under section 194P, because the bank deducts the tax.
← Previous Next: Which ITR Form Is Yours? ITR-1 to ITR-7 Explained →
03 Topic 3 of 20
Using the wrong form can make your return defective under section 139(9). The forms for AY 2026-27 were notified by CBDT in March 2026 and are listed on the e-filing downloads page. Find your form below. Each form has its own detailed guide.
Find your form with five quick questions:
For resident individuals with salary or pension, house property, interest and other sources. Total income must be up to ₹50 lakh. From AY 2026-27 it covers up to two house properties. Long-term gains under section 112A up to ₹1.25 lakh and agricultural income up to ₹5,000 are allowed. Not for directors, holders of unlisted shares, or people with foreign assets or losses to carry forward. Read our ITR-1 filing guide.
For individuals and HUFs with no business or professional income who cannot use ITR-1. Typical users sell shares or property, hold foreign assets, are company directors, are NRIs, or earn above ₹50 lakh. Read our ITR-2 filing guide.
For individuals and HUFs with business or professional income not declared on a presumptive basis. This includes F&O and intraday traders, partners in firms, and anyone keeping regular books. Read our ITR-3 filing guide.
For resident individuals, HUFs and firms (not LLPs) declaring income under section 44AD, 44ADA or 44AE. Total income must be up to ₹50 lakh. Like ITR-1, it now allows up to two house properties. ITR-4 is optional. Read our ITR-4 filing guide.
For partnership firms, LLPs, AOPs, BOIs, co-operative societies and similar entities. It is not for individuals, HUFs or companies. Firms and LLPs must file every year, even with nil income or a loss. Read our ITR-5 filing guide.
For companies, except those claiming exemption under section 11. It must be filed with a digital signature. Most companies also need a tax audit if turnover crosses the limit. Read our ITR-6 filing guide.
For persons filing under sections 139(4A) to 139(4D), such as charitable and religious trusts, political parties, research bodies, universities and similar institutions. Read our ITR-7 filing guide.
ITR-U is the updated return under section 139(8A), used to report income you missed earlier. ITR-B is the return for a block period under section 158BC, filed after a search or requisition. ITR-V is not a return at all. It is the acknowledgement the portal creates when you submit, and the page you post to CPC if you do not e-verify online.
Not sure? Our expert picks the form after reading your AIS, so you do not need to decide this yourself.
04 Topic 4 of 20
The new regime under section 115BAC is the default. The old regime allows more deductions but has higher rates. The official slab guide for AY 2026-27 lists both. For individuals below 60:
| New regime income slab | Rate | Old regime income slab | Rate |
|---|---|---|---|
| Up to ₹4 lakh | Nil | Up to ₹2.5 lakh | Nil |
| ₹4 lakh to ₹8 lakh | 5% | ₹2.5 lakh to ₹5 lakh | 5% |
| ₹8 lakh to ₹12 lakh | 10% | ₹5 lakh to ₹10 lakh | 20% |
| ₹12 lakh to ₹16 lakh | 15% | Above ₹10 lakh | 30% |
| ₹16 lakh to ₹20 lakh | 20% | ||
| ₹20 lakh to ₹24 lakh | 25% | ||
| Above ₹24 lakh | 30% |
Health and education cess of 4% applies on top. Surcharge applies above ₹50 lakh income.
Can you switch? If you have no business income, you can choose the regime every year in the ITR itself. But the old regime can be chosen only in a return filed by the due date under section 139(1). A belated return stays in the new regime. If you have business income, you opt out through Form 10-IEA before the due date. You can come back to the new regime only once. After that, the old regime stays closed while you have business income.
We run both calculations for you and show the numbers side by side before filing. Use our free calculators on the TaxCaller tools page for a first estimate.
← Previous Next: Benefits of Filing Your Return, Even When Tax Is Nil →
05 Topic 5 of 20
Many people skip the ITR when TDS has already been cut. That often costs them money and future trouble. Here is what a filed return does for you:
06 Topic 6 of 20

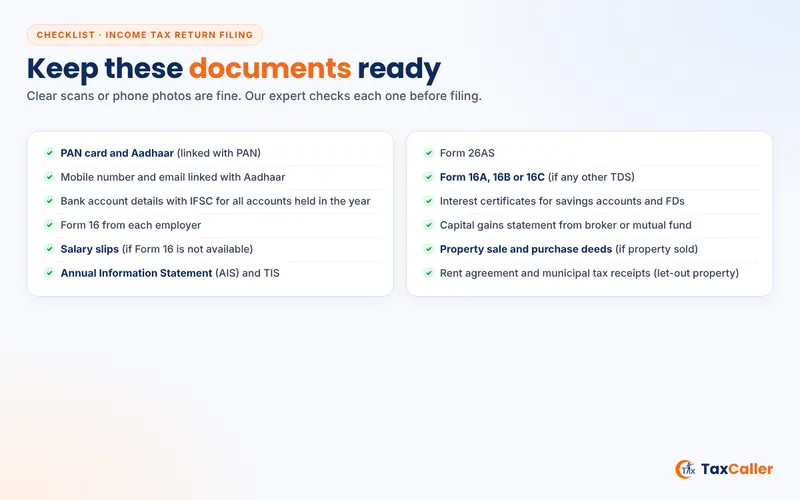
Keep these ready before we start. You can share clear photos or PDFs on WhatsApp or email.
Basic details (everyone)
Salary and pension
Tax statements from the portal
Other income
Business and profession
Deductions (old regime)
Read AIS, TIS and Form 26AS before you file:
Do not worry if a paper is missing. We tell you what matters for your case and what can be skipped.
← Previous Next: How TaxCaller Handles Your Income Tax Return Filing, Step by Step →
07 Topic 7 of 20

Our process is fully online. You do not need to visit any office.
What you receive once the return is filed:
How long does it take? For a salary return with complete papers, the computation is usually shared within a working day or two of receiving documents. Capital gains and business returns take longer because statements need checking. Your expert confirms the timeline on the first call.
← Previous Next: Filing It Yourself on the e-Filing Portal →
08 Topic 8 of 20
Some people prefer to file on their own. The department explains both modes on its file income tax return help page. Here is the short version.
Online mode
Offline mode
Download the common offline utility (JSON) or the Excel utility for your form from the downloads page. Import pre-filled data, fill all tabs, validate, and generate the JSON file. Then log in and upload it under the offline option. The Excel utility needs macros enabled.
When to get help: self-filing works well for a single salary with no other income. It gets tricky with capital gains, F&O, foreign assets, more than one employer, house property loss or a regime switch. One wrong schedule can trigger a defective return notice.
Doing it alone compared with an expert:
| Your situation | Filing yourself | Filing with our expert |
|---|---|---|
| One salary, no other income | Usually simple with pre-filled data | Helpful if you want both regimes checked |
| Two employers in one year | Easy to miss the double standard deduction | Both Form 16s combined and extra tax worked out |
| Shares, funds or property sold | Schedule CG and grandfathering need care | Broker statement read and gains split by type |
| F&O, intraday or freelance income | Turnover, audit limit and ITR-3 schedules to work out | Turnover computed and presumptive option compared |
| AIS shows entries you do not recognise | Risk of a mismatch notice later | Feedback filed and the return matched to AIS |
| A notice arrives after filing | You draft the reply alone | The same expert replies with your file in hand |
Abhinay Rai Income Tax Expert
Have a question on this topic? Ask Abhinay on a free call.
← Previous Next: E-Verification: The Step That Completes Your Return →
09 Topic 9 of 20
Uploading the ITR is not the end. A return that is not verified is treated as invalid. You must verify it within 30 days of uploading, as explained in the department's e-verification FAQ (CBDT Notification No. 2/2024).
Ways to verify:
If you verify late: the date of verification is treated as the date of filing. If that date falls after the due date, the return becomes a late return. Late fee and other effects follow. You can ask for condonation of delay on the portal if the reason was genuine.
← Previous Next: ITR Due Dates for AY 2026-27 (FY 2025-26) →
10 Topic 10 of 20
The Finance Act, 2026 rewrote the due date table in Explanation 2 to section 139(1). It now has four rows, and a new 31 August date for non-audit business cases. The official ITR help page explains these dates for AY 2026-27.
| Who | Usual form | Due date |
|---|---|---|
| Salaried people, pensioners, investors (no business income) | ITR-1, ITR-2 | 31 July 2026 |
| Business or profession, no tax audit, and partners of such firms | ITR-3, ITR-4, ITR-5 | 31 August 2026 |
| Companies, others whose accounts need audit, and partners of audited firms | ITR-3, ITR-5, ITR-6 | 31 October 2026, extended to 21 November 2026 |
| Cases with a transfer pricing report under section 92E | ITR-3, ITR-5, ITR-6 | 30 November 2026 |
| Belated return, section 139(4) | Same form | 31 December 2026 |
| Revised return, section 139(5) | Same form | 31 March 2027 |
| Updated return, section 139(8A) | ITR-U | 31 March 2031 |
The 21 November extension comes from CBDT Circular No. 07/2026 dated 28 September 2026. It also moved the tax audit report date under section 44AB to 21 October 2026.
A belated or revised return closes earlier if your assessment is completed before these dates. Also note that returns for AY 2025-26 and earlier years can no longer be filed as belated or revised returns after 1 April 2026. Only ITR-U is open for those years.
← Previous Next: Missed the Deadline? Belated, Revised and Updated Returns →
11 Topic 11 of 20
It is not too late. The law gives three ways to file or fix a return after the due date. Here is how the four return types compare for AY 2026-27.
| Return | Section | Last date | Extra cost |
|---|---|---|---|
| Original | 139(1) | 31 July, 31 August, 21 November (audit cases, extended) or 30 November 2026, by type of taxpayer | None if filed on time |
| Belated | 139(4) | 31 December 2026 | Late fee under 234F, interest under 234A |
| Revised | 139(5) | 31 March 2027 | Fee under 234-I if filed after 31 December 2026 |
| Updated (ITR-U) | 139(8A) | 31 March 2031 | Additional tax of 25% to 70% under 140B |
1. Belated return, section 139(4)
2. Revised return, section 139(5)
3. Updated return (ITR-U), section 139(8A)
Details, conditions and worked examples are on our updated return (ITR-U) filing page.
Tell us your situation on a call. We will say which route is cheapest and safest for you.
← Previous Next: Late Fees, Interest and Penalties for Late or Wrong Returns →
12 Topic 12 of 20

Here are the main charges under the Income-tax Act, 1961 for AY 2026-27:
| Provision | When it applies | Amount |
|---|---|---|
| Section 234F | Return filed after the due date | ₹5,000. Only ₹1,000 if total income is up to ₹5 lakh. |
| Section 234-I | Revised return filed after 31 December 2026 | ₹5,000. Only ₹1,000 if total income is up to ₹5 lakh. |
| Section 234A | Tax unpaid on the due date, return filed late | Simple interest of 1% per month or part month |
| Section 234B | Advance tax paid is less than 90% of tax | 1% per month on the shortfall |
| Section 234C | Advance tax instalments paid late or short | 1% per month on the deferred amount |
| Section 270A | Under-reported income | 50% of the tax on that income. 200% if income is misreported. |
| Section 276CC | Wilful failure to file in serious cases | Prosecution, with a jail term in law |
Other effects of late filing:
From Tax Year 2026-27, the same late fee moves to section 428 of the Income-tax Act, 2025.
← Previous Next: Income Tax Refunds: Status, Timeline and Interest →
13 Topic 13 of 20
A refund is due when TDS, TCS or advance tax is more than your final tax. You claim it only through the ITR.
How the refund reaches you
Timeline: the law does not give a fixed number of days. Simple returns are often processed within a few weeks. Processing under section 143(1) can take up to nine months from the end of the financial year in which you filed.
Interest: under section 244A, you get simple interest of 0.5% per month on the refund, from 1 April of the assessment year if you filed on time, or from the filing date if you filed late.
Common reasons for refund delay:
What the refund status means:
You can check status after login under e-File, then Income Tax Returns, then View Filed Returns. We track it for you and act if it gets stuck.
← Previous Next: Income Tax Notices After Filing and How to Respond →
14 Topic 14 of 20
A notice is not always bad news. Most are system messages that need a clear reply. Common ones are:
| Notice | What it means | What to do |
|---|---|---|
| Intimation u/s 143(1) | CPC's result after processing | Check it against your return. If there is a demand you disagree with, file a rectification under section 154 or respond online. |
| Defective return u/s 139(9) | Wrong form, missing schedule or tax not paid | Correct and refile within 15 days of the notice, or the return may be treated as not filed. |
| Proposed adjustment u/s 143(1)(a) | Mismatch with AIS, 26AS or Form 16 | Agree or disagree online within 30 days with reasons. |
| Request for information u/s 133(6) | The department wants details of a transaction | Send the details asked for by the date given. |
| Notice u/s 142(1) | Inquiry before assessment, asking for documents or a return | Reply on the e-proceedings tab by the date in the notice. |
| Intimation u/s 245 | Proposal to adjust your refund against an old demand | Agree, or disagree with proof, by the date in the intimation. |
| Scrutiny notice u/s 143(2) | Detailed check of your return | Reply with documents through the e-proceedings tab. |
| Notice u/s 148A or 148 | Income may have escaped tax | Get expert help quickly. Time limits are strict. |
Under the transition rules, defective return notices and scrutiny notices for AY 2026-27 continue under the 1961 Act.
We help clients read and answer routine notices linked to returns we filed. For any other notice, our income tax notice reply service drafts and files the response. Complex scrutiny or reassessment work is quoted separately after we see the notice.
← Previous Next: Common Mistakes That Lead to Defective Returns or Notices →
15 Topic 15 of 20
← Previous Next: Special Cases: Capital Gains, F&O, Crypto, NRIs and No Form 16 →
16 Topic 16 of 20
Capital gains on shares and mutual funds: short-term gains on listed equity under section 111A are taxed at 20%. Long-term gains under section 112A are taxed at 12.5% above ₹1.25 lakh a year. Grandfathering and indexation rules can apply on older assets and property. We read your broker's tax P&L and fill Schedule CG.
F&O and intraday: these are business income. You file ITR-3, and a tax audit may apply above certain turnover limits. F&O losses can be carried forward for eight years, and intraday (speculative) losses for four years, but only if the return is filed on time.
Crypto and other virtual digital assets: gains are taxed at a flat 30% under section 115BBH, with no set-off of losses. TDS of 1% under section 194S shows in AIS and must match.
NRIs: NRIs file ITR-2 or ITR-3 for Indian income such as rent, interest, capital gains or business. Treaty benefits and lower TDS claims need care. ITR-1 and ITR-4 are not available to NRIs.
Pensioners and senior citizens: section 80TTB allows up to ₹50,000 deduction on deposit interest in the old regime. Form 15H can stop TDS when income is below the limit.
Filing without Form 16: this is common for people who changed jobs or worked for small employers. We use salary slips, bank credits and Form 26AS to work out salary income. Exemptions like HRA need proof.
Freelancers and small businesses: section 44ADA lets eligible professionals declare 50% of receipts as income. Section 44AD covers small businesses. If your business also needs GST work, see our GST return filing service.
HUFs: a Hindu Undivided Family has its own PAN and files its own return, usually ITR-2 or ITR-3.
← Previous Next: What Changed in 2026 for Income Tax Return Filing →
17 Topic 17 of 20
2026 brought the biggest change to Indian income tax law in six decades. Here is what matters for you:
Many form numbers also change under the Income-tax Rules, 2026 for Tax Year 2026-27. We map them for you, so your 2027 filing goes smoothly.
18 Topic 18 of 20
TaxCaller charges a professional fee for each return. It depends on your form and income sources. The table shows the starting fee for each service. If your case needs more work, our expert tells you the exact fee before anything starts.
| Service | Suited to | Starts at |
|---|---|---|
| ITR-1 filing | Salary or pension, up to two houses, interest; income up to ₹50 lakh | ₹799 + GST |
| ITR-2 filing | Capital gains, NRIs, directors, foreign assets, income above ₹50 lakh | ₹1,874 + GST |
| ITR-3 filing | Business or profession with books, F&O and intraday | ₹2,999 + GST |
| ITR-4 filing | Presumptive income under 44AD, 44ADA or 44AE | ₹1,999 + GST |
| ITR-5 filing | Partnership firms, LLPs, AOPs and BOIs | ₹2,999 + GST |
| ITR-6 filing | Private and public companies | ₹3,999 + GST |
| ITR-7 filing | Trusts, institutions and political parties | ₹4,999 + GST |
| Updated return (ITR-U) | Missed income from up to four earlier years | ₹1,799 + GST |
| Income tax notice reply | Intimations, defective return and mismatch notices | ₹2,099 + GST |
| TDS return filing | Quarterly salary TDS return (24Q) for small employers | ₹999 + GST |
| Tax consultant | A 30-minute call with a tax expert, answer in writing | ₹799 + GST |
What every ITR plan includes: Form 16, AIS and 26AS matching, old vs new regime comparison, filing, and help with e-verification. Higher plans add capital gains working, presumptive income, advance tax checks, P&L and balance sheet, and loss carry-forward where allowed.
Government fees are separate. The Income Tax Department charges no fee to file a return on time. Any amount payable to the government is paid by you directly at actual. This includes tax, interest under sections 234A, 234B and 234C, late fee under section 234F, revised return fee under section 234-I and additional tax on ITR-U. These are never part of TaxCaller's fee.
Work outside these services, such as tax audit, scrutiny or reassessment, or many years of back filing, is quoted in writing before we begin.
← Previous Next: Why People Choose TaxCaller for ITR Filing →
19 Topic 19 of 20
Have a broader tax question beyond the return? Speak to our tax consultant team.
← Previous Next: After Filing: Ongoing Tax Compliance and Related Services →
Real experts, not a call centre
Your work is handled by experienced professionals who explain every step, check your documents and keep you updated.
Registered company
TaxCaller is run by TaxCaller India LLP (LLPIN AAQ-7388), serving clients since 2018.
Fee told upfront
You know the complete fee, our professional fee and the government fee, before any work starts. No hidden charges.
Support after the work
Notices, renewals, returns and compliance reminders: we stay with your business after the registration is done.
Reviewed & Verified Income Tax Return Filing
Abhinay Rai
Advocate
Abhinay Rai is a Advocate specialising in Income Tax Return Filing. The process, documents, timelines and fees on this page are checked against the current rules and government portals, and updated whenever the law, forms or fees change.
For AY 2026-27, salaried people and investors had to file by 31 July 2026. Non-audit business and professional cases had until 31 August 2026. Audit cases now have until 21 November 2026 under CBDT Circular 07/2026. Transfer pricing cases have until 30 November 2026. Anyone who missed their date can file a belated return until 31 December 2026.
Yes. You can file a belated return under section 139(4) until 31 December 2026 for AY 2026-27. You pay a late fee of ₹5,000, or ₹1,000 if income is up to ₹5 lakh. Interest applies on unpaid tax. You also lose the old regime option and the carry forward of most losses. After that, only ITR-U remains.
Usually yes. The ₹12 lakh figure is the rebate limit under section 87A in the new regime, not the filing limit. Filing is required when income before deductions is more than ₹4 lakh in the new regime. So a person earning ₹10 lakh may owe zero tax but must still file a return on time.
Most salaried residents with income up to ₹50 lakh use ITR-1. From AY 2026-27, it allows up to two house properties. It also accepts long-term gains on listed shares up to ₹1.25 lakh. You need ITR-2 if you sold shares within a year, hold foreign assets, are a company director or earn above ₹50 lakh.
Yes. Form 16 is helpful but not compulsory. We work out your salary from salary slips, bank credits and the TDS shown in Form 26AS and AIS. If your employer cut no TDS, the salary still has to be reported. Exemptions like HRA need rent receipts and other proof, which you should keep safely.
Simple, e-verified returns are often processed within a few weeks, but the law sets no fixed time. Processing under section 143(1) can take up to nine months from the end of the year of filing. Delays usually come from a bank account not pre-validated, an inoperative PAN or a TDS mismatch. Interest is paid under section 244A.
An unverified return is treated as invalid, as if you never filed. You must verify within 30 days of uploading. If you verify later, the verification date counts as the filing date. If that is after the due date, the late fee and other late filing effects apply. Aadhaar OTP is the quickest way to verify.
If you have no business or professional income, yes. You choose the regime each year in the return, but the old regime is allowed only in a return filed by the due date. With business income, you opt out using Form 10-IEA. You can come back to the new regime only once, and then the old regime stays closed.
The late fee under section 234F is ₹5,000, or ₹1,000 if total income is up to ₹5 lakh. Interest under section 234A runs at 1% per month on unpaid tax. If income is under-reported, penalty under section 270A can be 50% of the tax, and 200% for misreporting. Serious failures can lead to prosecution.
File a revised return under section 139(5). For AY 2026-27, you can revise until 31 March 2027 or until assessment is complete. A revision after 31 December 2026 carries a fee under section 234-I of ₹1,000 or ₹5,000. If the window has closed, an updated return can report missed income, with extra tax.
No. AY 2026-27 covers income earned from April 2025 to March 2026, filed in 2026 under the Income-tax Act, 1961. Tax Year 2026-27 covers income from April 2026 to March 2027, filed in 2027 under the Income-tax Act, 2025. They are different years and need separate returns at different times.
The Annual Information Statement shows what banks, employers, brokers and others reported about you, such as interest, dividends, share sales, rent and TDS. The department compares your return with it. Any income in AIS left out of your ITR can bring a notice. You can give online feedback if an AIS entry is wrong.
An NRI must file if Indian income is above the basic exemption limit, such as rent, interest, capital gains or business income. NRIs also file to claim refunds of extra TDS, which is common on property sales and NRO interest. They use ITR-2 or ITR-3, since ITR-1 and ITR-4 are only for residents.
Yes. A tax professional can prepare and upload your return with your consent, using your login or as an authorised intermediary on the portal. You still need to share correct details and verify the return yourself, usually through Aadhaar OTP. TaxCaller's experts prepare the computation, take your approval, file it, and guide you through verification.
Our starting fee is ₹799 + GST for a salary return in ITR-1. ITR-2 starts at ₹1,874, ITR-4 at ₹1,999, ITR-3 and ITR-5 at ₹2,999, ITR-6 at ₹3,999 and ITR-7 at ₹4,999, all + GST. Filing on the portal has no government fee, but any tax, interest or late fee is paid separately at actual.
Local experts, the same fixed process and fee. Choose your city.
Book a free call. We tell you the right ITR form, the better regime and our fee upfront, then file and help you e-verify.
Mon–Fri 9:00 AM – 6:00 PM, Sat 10:00 AM – 4:00 PM · Your trust is our biggest fee.